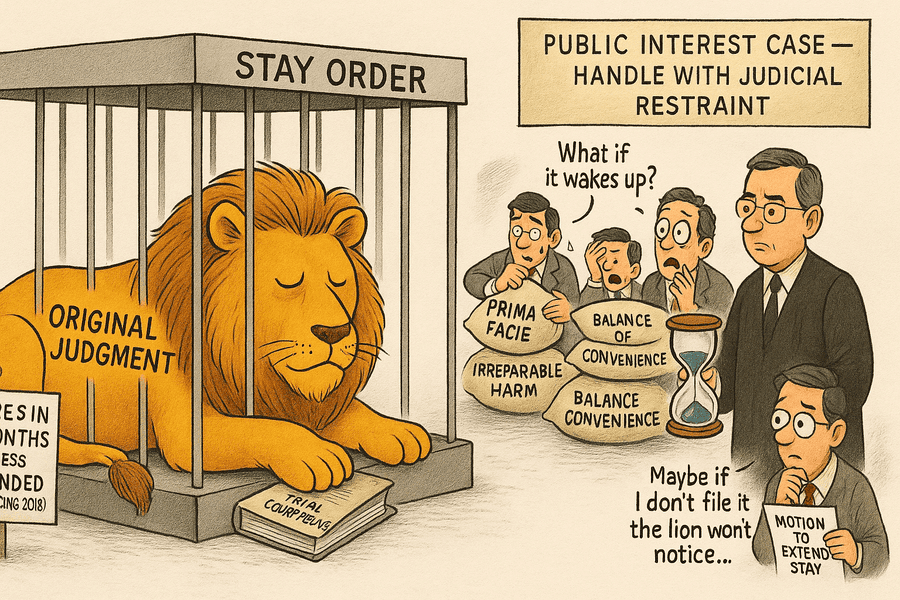
Stay orders are temporary judicial interventions that pause enforcement of lower court judgments while appeals are pending, not permanent dismissals. Indian courts grant stays only when specific conditions are met: prima facie case, balance of convenience, and irreparable injury. As established in Asian Resurfacing (2018), stays automatically lapse after six months unless extended with recorded reasons. The Supreme Court emphasizes judicial restraint in granting stays, particularly in public interest matters. While stays preserve status quo and prevent irreparable harm during proceedings, they don’t determine case merits. Once vacated, the original judgment becomes immediately enforceable – a “sleeping lion that awakens.”
A stay order temporarily suspends the effect of a ruling, preserving the status quo while legal proceedings continue
The Indian judicial system, with its hierarchical structure of courts, provides various remedies to ensure justice and prevent irreparable harm during the pendency of legal proceedings. Among these remedies, the concept of ‘stay orders’ holds particular significance. Often misunderstood as a permanent solution, stay orders are essentially temporary judicial interventions that suspend the operation of a judgment, order, or legal proceeding while the matter is under review by a higher court.
Understanding the Nature of Stay Orders
A stay order is fundamentally different from a dismissal or quashing of a lower court’s decision. While the latter permanently invalidates a judicial pronouncement, a stay merely puts it on hold. This distinction was eloquently clarified by the Supreme Court in Asian Resurfacing of Road Agency Pvt. Ltd. v. Central Bureau of Investigation (2018) 16 SCC 299, where the Court observed that “a stay order does not render a decision of the lower court a nullity; it only suspends the enforceability of the order/judgment.”
The temporary nature of stay orders is rooted in the principle of maintaining status quo ante, preventing any party from suffering irreparable injury during the pendency of proceedings. The Supreme Court in Mulchand Deva Ram Chawla v. State of Gujarat (1974) 3 SCC 698 held that “the very purpose of a stay order is to preserve the subject matter of the appeal and to ensure that the appeal, if successful, is not rendered infructuous.”
Legal Framework Governing Stay Orders
The power to grant stay orders derives from multiple statutory provisions and inherent powers of courts. Under the Civil Procedure Code, 1908, Order XLI Rule 5 specifically empowers appellate courts to stay proceedings in execution of decrees. Section 151 of the CPC also provides inherent powers to courts to make such orders as may be necessary for the ends of justice.
In criminal matters, Section 397 read with Section 401 of the Code of Criminal Procedure, 1973, empowers High Courts and Sessions Courts to stay orders of subordinate courts during revision proceedings. Similarly, Article 226 and Article 227 of the Constitution vest High Courts with supervisory jurisdiction, including the power to grant interim stay orders.
The Supreme Court, under Article 136 of the Constitution, exercises its special leave jurisdiction and frequently grants stay orders pending final disposal of special leave petitions. In Gangadhar v. Raghunath (1981) 4 SCC 103, the Supreme Court emphasized that “the power to grant interim relief, including stay orders, is incidental to the main power of the Court to do complete justice between the parties.”
Conditions for Granting Stay Orders
Courts do not grant stay orders mechanically or as a matter of routine. The Supreme Court in Shiv Shakti Coop. Housing Society v. Swaraj Developers (2003) 6 SCC 659 laid down three essential conditions for granting stay:
A prima facie case in favor of the applicant
Balance of convenience tilting in favor of the applicant
Irreparable injury likely to be caused if stay is not granted
The Court further clarified that these conditions are cumulative and not alternative. The mere filing of an appeal or revision petition does not automatically entitle a party to a stay order. In Atma Ram v. State of Punjab (1959) SCR 1 SC, the Supreme Court held that “stays should be granted only in exceptional circumstances and not as a matter of course.”
Duration and Limitations of Stay Orders
Recognizing that prolonged stays can defeat the purpose of justice, courts have imposed temporal limitations on stay orders. The Supreme Court in Asian Resurfacing of Road Agency (supra) directed that any stay granted by any court, including the High Court, shall automatically lapse after six months unless extended for good reasons to be recorded in writing.
This landmark judgment aimed to prevent the misuse of stay orders, which often resulted in cases remaining pending for years. The Court observed that “stay orders cannot be allowed to operate indefinitely and defeat the very purpose of expeditious disposal of cases.”
In Commissioner of Central Excise v. Dunlop India Ltd. (1985) 1 SCC 260, the Supreme Court held that interim orders should not be continued mechanically without considering changed circumstances. The Court emphasized that “an interim order which was passed at an earlier stage may require modification or vacation in view of subsequent developments.”
Stay Orders versus Merits of the Case
It is crucial to understand that granting a stay order does not reflect upon the merits of the main case. The Delhi High Court in Rajiv Mehrotra v. Suresh Mehrotra 175 (2010) DLT 289 clarified that “grant of stay is not a reflection on the merits of the case, but is aimed at preserving the subject matter and preventing prejudice to parties during pendency of proceedings.”
The distinction between interim relief and final adjudication was highlighted by the Supreme Court in State of Maharashtra v. Digambar (1995) 4 SCC 683, where it held that “while granting interim relief, the Court does not decide the controversy on merits but merely preserves the property in dispute to await the final outcome of the proceedings.”
Vacation and Modification of Stay Orders
Stay orders, being temporary in nature, are subject to vacation or modification. The Supreme Court in M/s. Transcore v. Union of India (2006) 6 SCC 224 held that “a party can always approach the Court for vacation or modification of stay orders if there is change in circumstances or if the stay is being misused.”
Courts have inherent power to recall or modify their own orders, including stay orders. In Grindlays Bank Ltd. v. Income Tax Officer (1980) 2 SCC 191, the Supreme Court observed that “the power to grant stay necessarily implies the power to vacate or modify it when circumstances warrant such action.”
Impact on Lower Court Proceedings
When a stay order is issued, the proceedings or execution of orders of lower courts are temporarily suspended, but the original judgment remains intact. The Supreme Court in Kunhayammed v. State of Kerala (2000) 6 SCC 359 clarified that “a stay order does not wipe out the order of the lower court; it only suspends its operation.”
This principle ensures that if the appeal or revision is dismissed, the original order springs back to life without requiring any fresh proceedings. The Karnataka High Court in Smt. Leelavathi v. M. Chandrashekar ILR 2006 KAR 3426 aptly noted that “a stayed order is like a sleeping lion which wakes up the moment stay is vacated.”
Stay Orders in Different Jurisdictions
The principle that stay orders are temporary measures is consistent across various branches of law. In taxation matters, the Supreme Court in Commissioner of Income Tax v. Vallabh Glass Works Ltd. (1983) 2 SCC 410 held that “stay of recovery proceedings does not amount to stay of assessment; the assessment order remains valid and enforceable once the stay is lifted.”
In service law jurisprudence, the Supreme Court in State of Uttar Pradesh v. Brahm Datt Sharma (1987) 2 SCC 179 observed that “stay of operation of an order of punishment does not amount to setting aside the order; it merely postpones its implementation.”
Judicial Restraint in Granting Stays
Courts have increasingly emphasized the need for judicial restraint in granting stay orders. The Supreme Court in Siliguri Municipality v. Amalendu Das (1984) 2 SCC 436 cautioned that “courts should be extremely careful and circumspect in granting stay orders as they tend to upset the normal course of administration of justice.”
The principle of judicial restraint is particularly important in matters involving public interest. In State of Karnataka v. State of Tamil Nadu (2017) 3 SCC 362, the Supreme Court held that “while considering stay applications in matters of public importance, courts must balance private interests against larger public good.”
Abuse of Stay Orders and Judicial Response
The Indian judiciary has been cognizant of the potential misuse of stay orders. In T.N. Godavarman Thirumulpad v. Union of India (2006) 1 SCC 1, the Supreme Court expressed concern over the “stay order culture” and emphasized the need for stricter scrutiny before granting stays.
To prevent abuse, courts have started imposing conditions while granting stays. In Deccan Airways Ltd. v. Air Aviation Inter-City Services (1986) 3 SCC 423, the Supreme Court upheld the practice of imposing monetary conditions or requiring security deposits while granting stay orders.
Conclusion
The jurisprudential understanding of stay orders in India clearly establishes their temporary and provisional nature. They serve as a crucial tool for preserving the rule of law and preventing irreparable harm during the pendency of legal proceedings. However, they are not and cannot be construed as permanent relief or as a judgment on the merits of the case.
The evolution of judicial thinking on stay orders reflects a careful balance between providing necessary interim relief and ensuring that justice is not delayed indefinitely. The recent trend of imposing time limits on stay orders and requiring periodic review demonstrates the judiciary’s commitment to preventing their misuse while maintaining their effectiveness as a tool for interim relief.
As the Supreme Court eloquently stated in Mohd. Mehtab Khan v. Khushnuma Ibrahim Khan (2013) 9 SCC 221, “Stay is a temporary phase. It is an order to preserve the status quo till the matter is finally decided. It does not determine any right and is meant only to grant temporary relief.” This fundamental principle continues to guide the Indian judiciary in its approach to stay orders, ensuring that they remain true to their intended purpose as temporary judicial interventions rather than permanent solutions.
The clear jurisprudential position is that stay orders are bridges, not destinations – they facilitate the journey to justice but are not the final resting place of judicial determination. Understanding this distinction is crucial for both legal practitioners and litigants in navigating the Indian judicial system effectively.
You’re trying to have a crucial conversation about your future, your rights, your very existence—but the person you’re talking to has their fingers in their ears, humming loudly. Now imagine that person is your democracy.
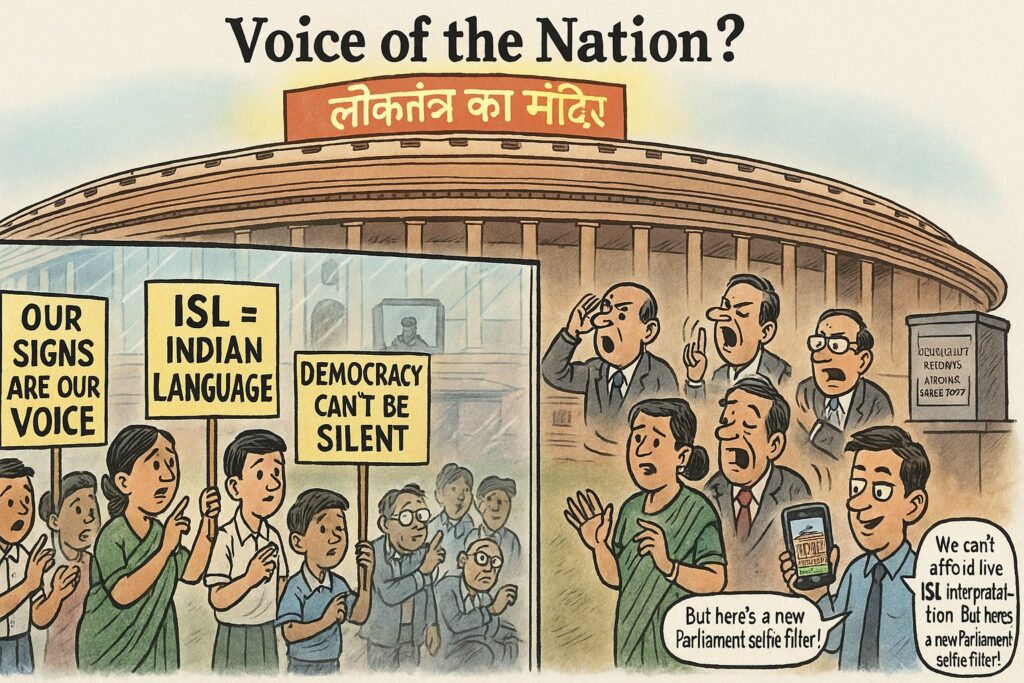
Welcome to the reality faced by millions of deaf and hard-of-hearing citizens worldwide, where the halls of power might as well be soundproof chambers designed to keep certain voices—or rather, certain hands—from joining the conversation.
The Great Parliamentary Pantomime
Our modern democracies pride themselves on being bastions of representation and inclusion. Politicians wax lyrical about being the “voice of the people,” but here’s the kicker: what happens when your voice speaks through signs rather than sounds? Suddenly, that meticulously crafted democratic machinery starts looking less like a well-oiled machine and more like a members-only club with a strict “No Hands Allowed” policy—unless you’re applauding, of course.
The irony is almost too perfect to be real. In chambers designed for debate, discussion, and the free exchange of ideas, we’ve somehow managed to create a system that systematically excludes those who communicate through the world’s most expressive medium: sign language. It’s as if we’ve built the world’s most sophisticated telephone system and forgotten that not everyone can hear the dial tone.
The Constitutional Conundrum
Here’s where things get legally spicy. Most democratic constitutions guarantee freedom of expression and the right to information. They’re beautiful documents, really—pages upon pages of rights and protections that would make any civil libertarian weep tears of joy. But there’s a catch, and it’s a big one: these rights assume you can access the very forums where they’re discussed, debated, and decided upon.
It’s like being invited to a dinner party where the menu is written in invisible ink. Sure, you’re technically included, but good luck figuring out what’s being served.
The legal gymnastics required to justify this exclusion would make even the most flexible constitutional lawyer pull a muscle. How do we square the circle of claiming universal representation while simultaneously making our most important democratic institution inaccessible to millions? The answer, it seems, is we don’t—we just hope nobody notices the contradiction.
The Technology Excuse That Isn’t
“But it’s too technically challenging!” cry the parliamentary administrators, clutching their pearls and their outdated broadcasting equipment. This argument might have held water in, say, 1975. But in an age where we can live-stream from Mars and run entire businesses from our phones, claiming we can’t add sign language interpretation to a video feed is like saying we can’t put wheels on a cart because we haven’t invented the circle yet.
The technology exists. It’s not just available; it’s embarrassingly simple. We’re not asking for holographic translators or AI-powered sign language robots (though those would be cool). We’re asking for what essentially amounts to picture-in-picture technology—something your grandmother’s TV from 1995 could handle.
The Global Report Card: Who’s Signing, Who’s Slacking
Let’s take a world tour of parliamentary accessibility, shall we? Spoiler alert: it’s not pretty.
New Zealand gets a gold star—they’ve had sign language interpretation in Parliament since 2006. Not coincidentally, they also recognized New Zealand Sign Language as an official language that same year. It’s almost as if treating a language as legitimate leads to actually using it in important places. Revolutionary concept, I know.
The United Kingdom stumbles along with sporadic interpretation for major events but falls short of comprehensive coverage. It’s like they’re saying, “We’ll include you, but only for the highlight reel.”
The United States Congress? Don’t make me laugh. In a country that prides itself on accessibility laws, the highest legislative body remains stubbornly monolingual in its broadcast approach. The Americans with Disabilities Act apparently stops at the Capitol steps.
The Cost-Benefit Analysis Nobody Wants to Do
“It’s too expensive!” comes the next cry from the budget hawks. Ah yes, the cost argument—the last refuge of those who’ve run out of real excuses. Let’s crunch some numbers, shall we?
The average cost of adding sign language interpretation to a broadcast is roughly equivalent to what most parliaments spend on coffee and biscuits for a month. We’re not talking about building a new wing; we’re talking about hiring qualified interpreters and adding a small video overlay.
But let’s flip the script: what’s the cost of excluding millions of citizens from democratic participation? How do you quantify the loss of civic engagement, the erosion of trust, the fundamental disconnect between the governed and their government? Suddenly that interpreter’s salary starts looking like the bargain of the century.
The Deaf Community: Not Silent, Just Unheard
Here’s the thing about the deaf community: they’re anything but silent. They’re vibrant, vocal (in their own way), and politically engaged. They march, they advocate, they organize. They do everything we expect active citizens to do—except they do it in a language that makes certain people uncomfortable because it doesn’t involve sound waves.
The cruel irony is that sign languages are among the most expressive and nuanced forms of human communication. They convey emotion, emphasis, and subtlety in ways that spoken language often struggles to match. Yet we’ve decided that our parliaments—places supposedly dedicated to passionate debate and eloquent expression—should remain off-limits to this rich form of discourse.
The Ripple Effect: Democracy’s Echo Chamber
When we exclude deaf citizens from parliamentary observation, we don’t just limit their access—we impoverish our entire democratic discourse. Every perspective we shut out, every voice (or hand) we ignore, makes our democracy a little less representative, a little less legitimate.
It creates a cascade effect. Young deaf children grow up knowing that the most important discussions in their country happen in places they cannot fully access. Is it any wonder that political disengagement becomes a self-fulfilling prophecy?
The International Legal Framework: Pretty Words, Ugly Reality
The UN Convention on the Rights of Persons with Disabilities is a masterpiece of international law. Article 21 specifically addresses the right to freedom of expression and access to information. Article 29 guarantees political participation. Countries around the world have signed it, ratified it, and promptly filed it away in the “good intentions” drawer.
The gap between our international commitments and our domestic realities is wide enough to drive a parliamentary motorcade through. We’re excellent at making promises on the global stage, less excellent at following through when the cameras are off.
The Path Forward: Solutions That Sign
So what’s the fix? It’s surprisingly straightforward:
First, recognize sign languages as official languages. Not honorary, not special status—official. If it’s good enough for millions of citizens to use daily, it’s good enough for parliament.
Second, implement comprehensive interpretation for all parliamentary proceedings. Not just the big speeches, not just the highlight moments—everything. Democracy doesn’t happen only during prime time.
Third, train and employ qualified interpreters. This isn’t a job for volunteers or well-meaning amateurs. Professional interpretation requires skill, stamina, and deep cultural understanding.
Fourth, make accessibility the default, not the exception. Stop treating inclusion as an add-on feature and start seeing it as fundamental architecture.
The Digital Age Advantage
Here’s where it gets exciting. Digital broadcasting and streaming technology have made accessibility easier than ever. We can offer multiple language tracks, customizable viewing options, and on-demand interpretation. The technical barriers that might have existed decades ago have evaporated like morning dew.
We’re living in an age where you can get real-time translation of spoken languages on your phone. Surely, we can manage to put a sign language interpreter in the corner of a parliament broadcast?
The Cultural Shift: From Accommodation to Integration
The real challenge isn’t technical or financial—it’s cultural. We need to stop seeing sign language interpretation as an accommodation and start seeing it as an integral part of how democracy functions. It’s not about being nice or charitable; it’s about being complete.
Imagine if we broadcast parliament in only one spoken language and told speakers of all other languages to just figure it out. There would be riots. Yet we do exactly this with sign languages and call it normal.
The Business Case for Democracy
Here’s an argument that might resonate with the economically minded: accessible democracy is good for business. When citizens feel included and engaged, they participate more fully in all aspects of society, including the economy. Exclusion breeds disengagement, and disengagement is expensive.
Countries that have embraced sign language accessibility report higher levels of civic participation among deaf citizens, better educational outcomes, and stronger social cohesion. It turns out that when you actually include people, they contribute more. Who knew?
The Momentum Is Building
The tide is turning, albeit slowly. Advocacy groups are getting louder (in every sense), legal challenges are mounting, and public opinion is shifting. The question isn’t whether parliaments will become fully accessible, but when and how gracefully they’ll make the transition.
The smart money is on the early adopters—the countries that recognize the writing on the wall (or the signing in the air) and move proactively to include all their citizens. The laggards will eventually be dragged along, but not before embarrassing themselves on the international stage.
The Bottom Line: Democracy That Speaks Everyone’s Language
Democracy is supposed to be a conversation. Not a monologue, not a lecture—a conversation. And conversations require that all parties can understand and be understood. When we exclude sign language users from parliamentary observation, we’re not just failing them; we’re failing the fundamental promise of democratic governance.
The solution isn’t complicated. It doesn’t require revolutionary technology or astronomical budgets. It requires something far more challenging: the willingness to see democracy as truly belonging to everyone, regardless of how they communicate.
When democracy doesn’t sign back, it’s not being silent—it’s being silencing. And in the grand theater of parliamentary democracy, that’s the one performance we can no longer afford to give.
The curtain is rising on a new act, one where every citizen has a front-row seat and nobody needs to strain to understand what’s happening on stage. The only question is: will our parliaments learn their lines in time?
Democracy that excludes is democracy that fails. It’s time to sign a new social contract—one that actually includes all the signatures.
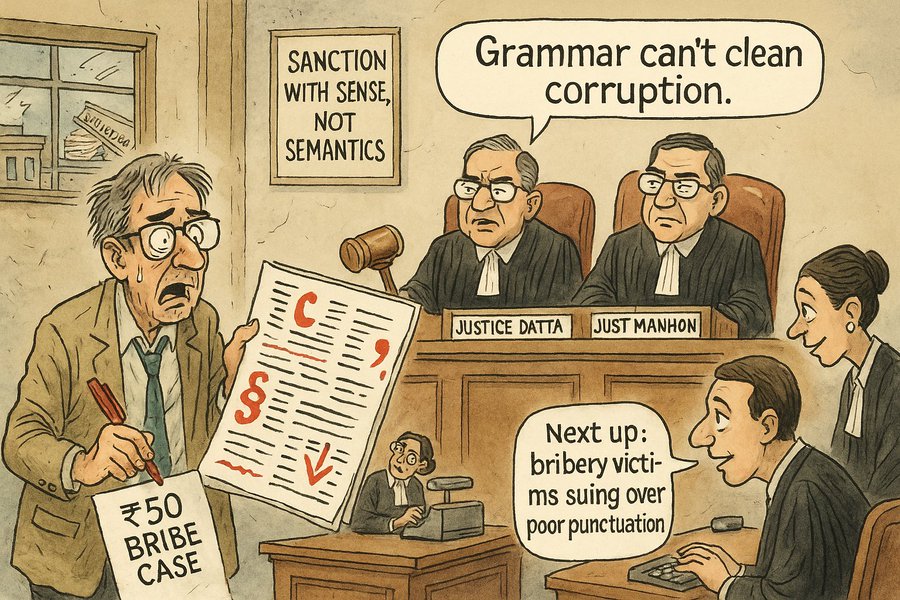
In a ruling that might disappoint grammar pedants everywhere, the Supreme Court has declared that minor edits don’t constitute a get-out-of-jail-free card for corrupt officials.
The Case of the Contested Commas
The Supreme Court recently dashed the hopes of a retired public servant who apparently believed that a red pen might accomplish what his defense counsel couldn’t. The official, convicted of accepting a modest ₹500 bribe back in 2000 (barely enough for a decent coffee these days), had pinned his acquittal hopes on alleged irregularities in the sanction order that authorized his prosecution.
Justices Dipankar Datta and Manmohan, clearly unimpressed by this editorial defense strategy, ruled that the minor tweaks made to the sanction report merely ensured its form matched its substance—a bit like adjusting your tie without changing your entire outfit.
Substance Over Style: The Court’s View
“If a draft order is placed before the sanctioning authority and he is satisfied that nothing needs to be added/deleted therefrom, the grant of sanction cannot be faulted merely on the ground of absence of addition of words to/deletion of words from the draft,” the Court declared, in what might be history’s most meta judicial statement about editing.
In essence, the Court concluded that the sanctioning authority had properly applied their mind before issuing the order—a refreshing assessment in bureaucratic circles, where “applying one’s mind” isn’t always a given.
The ₹500 Question
The case itself dates back to 2004 when a Special Court convicted the appellant for demanding and accepting a ₹500 bribe to expedite land record extracts. The Bombay High Court affirmed this conviction in September 2024, presumably after spending two decades contemplating the philosophical implications of a ₹500 bribe in an increasingly inflationary economy.
Before the Supreme Court, the appellant argued procedural flaws, including an allegedly “mechanical” sanction for prosecution—as if rubber stamps weren’t a time-honored tradition in government offices.
The Fine Print of Justice
Justice Datta, who authored the judgment, emphatically rejected claims that the sanction was granted without application of mind. The Court noted that sanctions exist to protect honest officials, not to provide a syntactical escape hatch for the dishonest ones.
“There is a legal impediment to prosecute a public servant for corruption, if there be no sanction,” the Court observed, before clarifying that all a sanctioning authority needs is to be satisfied about the existence of a prima facie case—not absolute certainty about every crossed ‘t’ and dotted ‘i’.
The Grammar of Corruption
Citing precedent from Manzoor Ali Khan v. Union of India, the bench emphasized that while procedural safeguards are important, they cannot become technical loopholes through which corruption slips unchecked.
“Even otherwise, merely because there is any omission, error or irregularity in the matter of granting sanction, that does not affect the validity of the proceedings unless the court records its own satisfaction that such error, omission or irregularity has resulted in a failure of justice,” the Court observed, essentially telling corruption defendants that their spell-check defense strategy needs a serious upgrade.
The Moral of the Story
In what might be considered a judicial version of “substance over form,” the Supreme Court has made it clear that minor alterations in a report, without any prejudice to substantial justice, don’t render a sanction order invalid.
For public servants contemplating similar appeals based on clerical technicalities, the message is crystal clear: editorial critiques won’t save you from corruption charges. Perhaps it’s better to simply avoid accepting bribes—even ones that wouldn’t cover a movie ticket in 2025’s economy.
The appellant, represented by Ms. Meenakshi Arora, senior counsel, might now be contemplating that ₹500 was an extremely expensive bribe—not for what it bought, but for what it ultimately cost.
Case Title: DASHRATH VERSUS THE STATE OF MAHARASHTRA
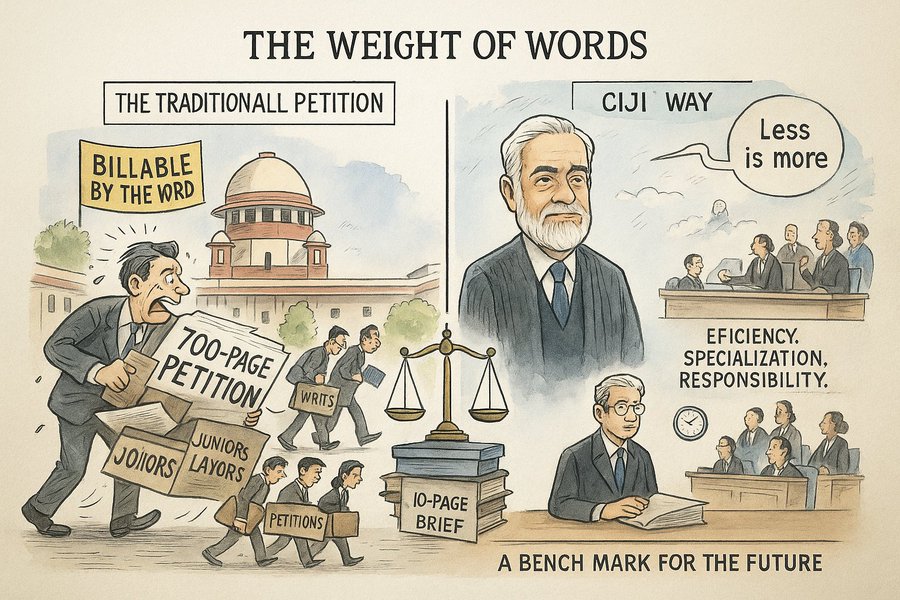
In a profession where words are the primary currency, the irony wasn’t lost on anyone when Chief Justice of India Sanjiv Khanna proclaimed that lawyers need to talk less—or at least write less. At a farewell function that could have easily devolved into ceremonial platitudes and nostalgic reminiscences, CJI Khanna instead delivered a masterclass on legal drafting that left many Advocates-on-Record (AoRs) frantically taking notes rather than clicking photographs.
“One thing I still feel we haven’t really mastered is the art of drafting,” declared CJI Khanna, his voice carrying the weight of countless nights spent wading through verbose petitions. “I feel a huge effort is required. We need to understand ‘less is more’…” The collective gulp from the audience was almost audible. In legal circles, where charging by the word has become something of an unspoken tradition, this was tantamount to suggesting barristers abandon their signature black robes.
European Efficiency vs. Indian Exuberance
To drive home his point, CJI Khanna shared an anecdote from his days as a practicing lawyer, when he drafted objections to an award in a European Court. With obvious pride, he mentioned drafting a mere “8 to 9 grounds” for objection—practically haiku-like brevity by Indian legal standards. Yet his European counterpart, likely stifling a chuckle, informed him that these would be further reduced to just three grounds. The reason? “The costs would be higher otherwise.”
This moment of cultural clash perfectly encapsulates the difference between European legal efficiency and Indian legal exuberance. While our European counterparts treat words as precious diamonds to be carefully selected and displayed, Indian legal documents often resemble a wholesale jewelry market where every conceivable ornament is on display, just in case something catches the judge’s fancy.
The Judicial Plea for Mercy
“We need to have crisper petitions. It helps us read the files more easily,” CJI Khanna continued, in what could only be interpreted as a judicial plea for mercy. One could almost visualize the Chief Justice’s chambers, buried under mountains of paperwork, each petition competing with the next in a Dickensian contest of verbosity.
The statement reveals a rarely acknowledged truth: judges are human beings with finite reading capacity and patience. Behind the grand robes and elevated benches are individuals who must process thousands of pages daily. CJI Khanna’s appeal wasn’t just professional advice; it was a humanitarian request.
The Curious Case of the Invisible AoRs
Having addressed the quantity of words, CJI Khanna turned his attention to who should be delivering them in court. In what might have caused several Senior Advocates to spill their coffee, he encouraged AoRs to argue matters themselves instead of merely serving as conduits to more experienced (and expensive) counsel.
“You have direct access to litigants. Why don’t you come and argue in the court yourself?” he asked pointedly. The question hung in the air like a challenge, addressing the elephant in the courtroom—the hierarchy that often relegates AoRs to background roles despite their intimate knowledge of cases.
This gentle provocation highlights a peculiar aspect of India’s legal ecosystem, where despite having invested considerable time and effort to earn the prestigious AoR qualification (which grants them exclusive right to file matters before the Supreme Court), many prefer to remain backstage, briefing Senior Advocates who then take center stage in courtrooms.
Specialization: The Antidote to Generalization
Never one to stop at criticism without offering solutions, CJI Khanna proceeded to prescribe a career development path for the assembled legal minds. “Domain specialization coupled with mastery of facts will take you ahead than oratory,” he advised, effectively dismantling the popular notion that successful lawyers are primarily silver-tongued orators.
“Every case does not need a huge constitutional principle. Most cases are decided on facts,” he added, a statement that might seem obvious but represents a paradigm shift in a legal culture often obsessed with grand constitutional interpretations over the nitty-gritty of factual details.
The CJI’s recommendation for mediation training further underscored his forward-thinking approach to legal practice. In a system notoriously burdened with backlogs, alternative dispute resolution mechanisms offer a promising avenue for both lawyers and litigants seeking quicker, less adversarial solutions.
The Succession of Mentorship
Perhaps the most poignant moment came when CJI Khanna spoke about mentorship. “Anyone with 15 years of experience must mentor juniors,” he said, introducing an almost mandatory element to what has traditionally been a voluntary relationship.
This statement reflects a growing concern about the sustainability of legal practice. As law firms grow larger and individual practice becomes more competitive, the art of mentorship—once the cornerstone of legal education—risks becoming a casualty of commercial pressures.
The Promise of Continued Guidance
In a touching moment that bridged his past and future, CJI Khanna offered his continued availability for legal consultation even after retirement. “If I have an office in the future, I will always be open to give legal advice. It will be my pleasure if you walk in and seek advice,” he said, revealing the mentor’s heart beating beneath the judge’s robe.
This offer stands in stark contrast to the common trajectory of retired judges, who often retreat into private arbitration practices or head government commissions. CJI Khanna’s willingness to remain accessible speaks volumes about his commitment to the development of legal practice beyond his tenure on the bench.
The Social Responsibility of Legal Privilege
CJI Khanna concluded his address with a reminder of lawyers’ social responsibility, urging them to provide free legal aid to those unable to afford it. “Lawyers have a license to practice law, but for that privilege and status, lawyers have an obligation to provide legal services to those without ability to pay…that should be the goal,” he emphasized.
In these words, CJI Khanna distilled the essence of legal practice—not merely as a profession or business, but as a service imbued with social responsibility. It was a fitting final note from a judge described by his successor, CJI-designate Justice Gavai, as embodying “transparency and inclusiveness.”
Legacy of Transparency
Justice Gavai’s tribute to CJI Khanna highlighted how he lived the principle that “the CJI is only the first amongst equals and not superior.” This praise was echoed by SCAORA President Vipin Nair, who drew parallels between CJI Khanna and his legendary uncle, Justice HR Khanna, known for his lone dissent during the Emergency—perhaps the most famous example of moral courage in Indian judicial history.
Nair specifically commended CJI Khanna for his transparency in handling the sensitive Justice Yashwant Varma issue, where “all documents” were put “in the public domain.” This reference to transparency in dealing with contentious matters within the judiciary itself demonstrates how CJI Khanna’s principles extended beyond mere courtroom management to institutional governance.
The Final Gavel
As CJI Khanna prepares to demit office on May 13, 2025, his farewell address serves not just as a goodbye but as a roadmap for the future of legal practice in India. From crisp drafting to specialized practice, from mentorship to social responsibility, he has outlined a vision that balances tradition with innovation, expertise with accessibility.
In a profession often accused of being resistant to change, CJI Khanna’s parting words serve as both challenge and inspiration. As the legal fraternity bids farewell to his leadership, the true measure of his impact will be seen in how many take his advice to heart—writing shorter petitions, arguing their own cases, specializing their practice, mentoring juniors, and extending legal services to those who need them most.
After all, in CJI Khanna’s own words, “less is more”—except, perhaps, when it comes to the scope of one’s professional ethics and social responsibility. There, more is indeed more.
In the complex landscape of Goods and Services Tax (GST) compliance, few areas demand as much attention as the issuance of tax invoices. For businesses engaged in providing continuous services spanning months or years, the timing of these invoices is governed by specific provisions under Section 31(5) of the Central Goods and Services Tax (CGST) Act, 2017. This provision contains three distinct sub-clauses that outline different scenarios for invoice issuance, raising important questions about their application: Do service providers have the freedom to choose which sub-clause to apply? Or are these provisions mutually exclusive and determined by contractual terms?
This article examines these questions and provides clarity on the correct application of Section 31(5) for continuous supply of services.
What Constitutes a “Continuous Supply of Services”?
Before delving into invoice timing requirements, it’s essential to understand what qualifies as a “continuous supply of services” under GST law. Section 2(33) of the CGST Act defines this as a service that is:
Provided continuously or on a recurrent basis
Under a contract
For a period exceeding three months
With periodic payment obligations
Typical examples include Annual Maintenance Contracts (AMCs), long-term software support agreements, rental arrangements extending beyond three months, and telecommunication services.
The Three Sub-clauses of Section 31(5): Understanding Their Distinct Applicability
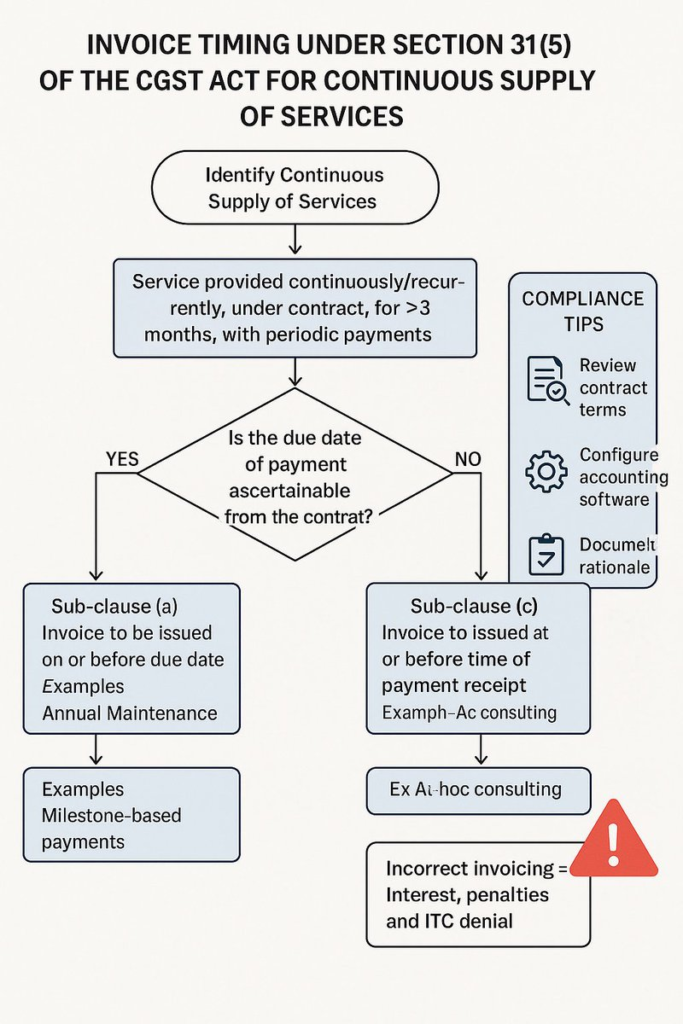
Section 31(5) provides three different scenarios for determining when to issue a tax invoice for continuous services:
Sub-clause (a): When Due Date is Ascertainable from Contract
The first scenario applies when the contract clearly specifies payment due dates. The provision states: “where the due date of payment is ascertainable from the contract, the invoice shall be issued on or before the due date of payment.”
For example, in a 12-month software maintenance contract with quarterly payments due on the 1st of April, July, October, and January, invoices must be issued on or before these specified dates.
Sub-clause (b): When Due Date is Not Ascertainable from Contract
The second scenario applies when the contract does not specify clear payment due dates. In such cases, “where the due date of payment is not ascertainable from the contract, the invoice shall be issued before or at the time when the supplier of service receives the payment.”
For instance, if a consulting agreement stipulates that payments will be made “based on fund availability” without fixed dates, the consultant must issue invoices before or when they receive payment.
Sub-clause (c): When Payment is Linked to Event Completion
The third scenario applies when payment depends on completing specific events: “where the payment is linked to the completion of an event, the invoice shall be issued on or before the date of completion of that event.”
An example would be a software development contract where 30% payment is due upon completion of “Phase 1: User Interface Design.” The invoice for this portion must be issued on or before the date Phase 1 is completed.
No Arbitrary Choice: Contractual Terms Determine Applicable Sub-clause
A critical question is whether service providers can arbitrarily choose which sub-clause to apply. The analysis of Section 31(5)’s structure and language reveals the answer is no.
Each sub-clause begins with the conditional term “where,” indicating that each provision is designed to apply to a specific and distinct factual scenario defined by the contract’s payment terms. This linguistic structure strongly suggests mutual exclusivity among the sub-clauses.
The conditions within each sub-clause—an ascertainable payment due date, a non-ascertainable due date, or payment linked to event completion—are inherently different. It’s difficult to conceive how a single payment obligation could simultaneously satisfy the distinct conditions of multiple sub-clauses.
Official circulars support this interpretation. For example, CBIC Circular No. 222/16/2024-GST addressing spectrum usage charges treats the Frequency Assignment Letter as a contract. The circular explicitly states that if this document specifies ascertainable payment due dates, Section 31(5)(a) mandatorily applies.
Therefore, the applicable sub-clause is determined by the objective contractual terms agreed between supplier and recipient, not by the service provider’s preference.
A Logical Assessment Process for Determining the Applicable Sub-clause
While Section 31(5) doesn’t explicitly establish a formal hierarchy among its sub-clauses, a logical sequence for their assessment emerges:
First, check whether the due date of payment is ascertainable from the contract. If yes, apply sub-clause (a).
If not, determine whether payment is linked to the completion of a specific event. If yes, apply sub-clause (c).
If neither of these conditions applies, default to sub-clause (b).
This structured approach ensures systematic coverage of all contractual payment possibilities.
Can Multiple Sub-clauses Apply to a Single Invoice?
Given the principle of mutual exclusivity, it’s highly improbable for more than one sub-clause to apply simultaneously to the same component of service covered by a single tax invoice.
However, a complex contract might involve different types of charges that, if invoiced separately, could legitimately fall under different sub-clauses. For example:
A fixed monthly retainer (Section 31(5)(a))
A performance bonus upon project phase completion (Section 31(5)(c))
Ad-hoc charges for additional services without fixed payment dates (Section 31(5)(b))
In such scenarios, different invoices would be issued for different service components, each following its relevant sub-clause. But for a single invoicing event covering a specific supply portion, only one sub-clause can apply.
Practical Implementation and Compliance Steps
To ensure compliance with Section 31(5), service providers should follow these steps:
Confirm “Continuous Supply” Status: Verify that the service meets all criteria under Section 2(33).
Thoroughly Examine the Contract: Review payment terms to determine which sub-clause applies:
Are payment due dates clearly ascertainable? → Apply sub-clause (a)
Are payments linked to specific event completions? → Apply sub-clause (c)
If neither condition applies → Apply sub-clause (b)
Document Your Rationale: Maintain internal records explaining why a particular sub-clause was applied, supported by relevant contract clauses.
Configure Accounting Systems: Ensure invoicing systems are set up to generate tax invoices according to the applicable timelines.
Handle Advance Payments Separately: Remember that receipt vouchers must be issued for any advance payments, independent of the tax invoice requirements under Section 31(5).
Consequences of Non-Compliance
Incorrect application of Section 31(5) can lead to several adverse outcomes:
Interest Liability: Delays in GST payment resulting from incorrect invoice timing can trigger interest charges (typically 18% per annum).
Penalties: Non-compliance may attract penalties under various provisions:
General penalty up to ₹25,000 under Section 125
Penalties for incorrect invoicing or non-issuance of invoices
Impact on Recipient’s Input Tax Credit (ITC): Perhaps most significantly, incorrectly issued or delayed invoices can jeopardize the recipient’s ability to claim ITC, potentially straining business relationships.
Increased Scrutiny: Persistent non-compliance may flag a business for departmental audits.
Why This Matters: Strategic Implications
The correct application of Section 31(5) carries significant strategic implications:
Contract Drafting Considerations: When negotiating continuous service agreements, parties should carefully consider how payment terms are structured, as this directly determines applicable invoicing timelines.
Cash Flow Impact: The timing of invoice issuance affects when GST liability arises and must be discharged, impacting cash flow planning.
Business Relationship Management: Ensuring timely and compliant invoicing facilitates smooth ITC claims for recipients, strengthening business relationships.
Risk Management: Proactive compliance minimizes the risk of penalties, interest, and disputes.
Conclusion
Section 31(5) of the CGST Act provides a structured framework for invoice timing in continuous service arrangements. The analysis leads to several key conclusions:
Service providers do not have arbitrary choice among sub-clauses (a), (b), and (c).
These sub-clauses are mutually exclusive, each addressing a distinct scenario based on contractual payment terms.
The contract is determinative—specific terms regarding payment due dates or event linkages dictate which sub-clause applies.
It’s not permissible to apply multiple sub-clauses to a single invoice for a specific supply component.
For businesses engaged in continuous services, implementing robust processes for contract review and invoice timing is essential. This includes thorough contract analysis, clear documentation of applicable provisions, appropriate system configuration, and regular monitoring of regulatory developments.
By embedding these compliance practices into contract management and operational processes, businesses can achieve more than mere technical adherence to GST provisions—they can create strategic advantage through enhanced financial planning, reduced risk exposure, and stronger client relationships.
The complexity of Section 31(5) reflects the diverse commercial arrangements that characterize continuous service supplies. However, with systematic analysis and structured implementation, businesses can navigate these requirements effectively while optimizing their invoicing practices within the legal framework.
In the shadowy corridors of India’s prison system, a silent tragedy unfolds daily. Over 1,650 children live behind bars—not because they’ve committed any crime, but simply because they were born to incarcerated mothers. These children, innocent yet imprisoned, represent the cruel intersection of justice and neglect, caught in a system that repeatedly promises reform but consistently fails to deliver.
“Prison Walls Cannot Obstruct Article 21”
“Prison walls cannot obstruct the onrush of the fruits of Article 21 for children.” These powerful words from the Allahabad High Court’s recent verdict in Smt Rekha v. State of UP (2025) encapsulate the fundamental constitutional promise made to these children. The case centered on a rejected bail application from an incarcerated mother of a five-year-old child completely dependent on her. While dismissing the mother’s plea, the court recognized something more profound—the systemic failure that forces children into prisons where their fundamental rights to dignity, healthcare, and education are routinely neglected.
As Justice Bhanot eloquently observed, “The collateral damage inflicted upon a child as a result of denial of bail to their parent becomes most significant when the child has to reside in prison with the accused parent.” This statement cuts to the heart of a legal paradox: in protecting society from alleged wrongdoers, the system creates innocent victims of its own.
Empty Promises: From Upadhyaya to Rekha
The tragic reality is that this isn’t the first judicial acknowledgment of the problem. In 2006, in the landmark case of RD Upadhyaya v. State of Andhra Pradesh, the Supreme Court established comprehensive guidelines for the care and treatment of children living in prisons. The Court mandated development initiatives, systematic medical care, education, and specialized housing for these children.
Yet nearly two decades later, the Rekha case exposes that little has changed. The same issues, the same constitutional clauses, and the same unresolved problems have resurfaced with disturbing persistence. Prison conditions continue to deprive children of proper educational facilities, despite the Right to Education being recognized as a fundamental right under Article 21-A since 2009.
As Justice Bhanot rightly observed, “Neglect of rights of children who suffer from such default confinement in jail will reflect the failure of the State and inadequacy of the judicial process.” This statement is not merely a legal observation but a damning indictment of institutional apathy.
The Psychological Price of Imprisonment
Perhaps most disturbing is what we’ve learned from research conducted in the aftermath of these judicial pronouncements. A 2015 psychological study on children of incarcerated women in Uttar Pradesh paints a harrowing picture of reality that contradicts the promised reforms.
The research revealed that “children in the prison struggled through numerous deficiencies that included nutrition, medical care, housing, schooling, and recreation,” despite the Supreme Court’s clear directions in RD Upadhyaya. More profoundly, it confirmed what should have been obvious: “a prison won’t ever offer a family atmosphere…children who reside with incarcerated mothers are in no way different compared to other children.”
Even more revealing was the finding that “kids who meet their parents who have separated on a frequent schedule exhibit greater emotional adaptation, greater I.Q. scores, and greater behavioural adjustment compared to those who do not.” This research underscores that these children not only need their parents but also need normalized interaction outside prison walls.
The Ticking Clock of Lost Childhood
For children outside the prison whose parents are incarcerated, time becomes “a slow, cruel ticking clock of starvation, apprehension and being abandoned.” The Tata Institute of Social Sciences (TISS) project called Prayas in Byculla Prison further investigated these conditions. When asked by the Allahabad High Court in Bachchey Lal v. State of UP (2014) to evaluate the circumstances of inmates in Uttar Pradesh, their findings echoed the 2015 psychological study’s dismal conclusions.
The High Court’s subsequent rulings reaffirmed several critical requirements that remain largely unimplemented:
Special dwelling units for children of incarcerated parents
Improved dietary and health offerings
A methodical framework for cooperation among probation officers, pediatric welfare organizations, and prison administration
Regular inspections to verify compliance with legal requirements
Prayas’ advocacy did lead to the Galabhet Programme (2016), allowing incarcerated mothers and their children to interact in person rather than through dehumanizing glass partitions. Yet this represents only a small victory in a much larger battle for these children’s rights.
The Evolution of Children’s Rights in Prisons
The journey toward recognizing children’s rights in confinement has been long and arduous. In 1987, the Supreme Court decision in Sheela Barse v. Children’s Aid Society broke open the closed door around conditions in observation homes. The Court established revision guidelines, emphasizing that children should not be seen as helpless objects of pity but as unique individuals with enforceable freedoms.
More recently, in Re: Right to Privacy of Adolescents (2023), the Supreme Court addressed concerns about children living with parents imprisoned under the Protection of Children from Sexual Offences (POCSO) Act. The Court determined that under Section 2(14) of the Juvenile Justice Act, these children must be identified as needing protection and care. Importantly, the ruling clarified that the State must intervene if a parent is deemed unsuitable to raise a child.
Rule 339(f) now requires children older than four to attend educational institutions outside prisons—a significant step toward normalizing their lives. More importantly, it eliminates parental choice; incarcerated parents cannot refuse to send their children to school. As the regulation firmly states: “Every child residing in jail with their parents will be compulsorily admitted to school.”
Children Growing Up Forgotten
The stark statistics tell a disturbing story: 27.5% of children incarcerated in Maharashtra alone have been identified as underweight. While the UP Jail Manual of 2022 mandates that jails include nurseries and crèches, the reality on the ground tells a different story.
The advocacy organization Prayas continues to fight for improved protections. In 2017, their PIL in the Bombay High Court led to orders protecting the property rights of arrested women, helping prevent homelessness after release. Yet the pattern of systemic indifference persists.
As Justice YK Sabharwal famously commented, these children “have to stay in jail with their mothers, through no fault of their own.” This observation cuts to the heart of the matter—these are innocent victims of a system that seems incapable of finding alternatives.
The truth remains inescapable: these children don’t only grow up in jails; they grow up forgotten. They represent not just a failure of prison policy but a moral failure of our society to protect its most vulnerable members. Until meaningful implementation of court guidelines takes place, the gap between judicial promises and prison realities will continue to claim these innocent childhoods.
The question remains: how many more generations of children must grow up behind bars before we transform judicial rhetoric into meaningful reform?
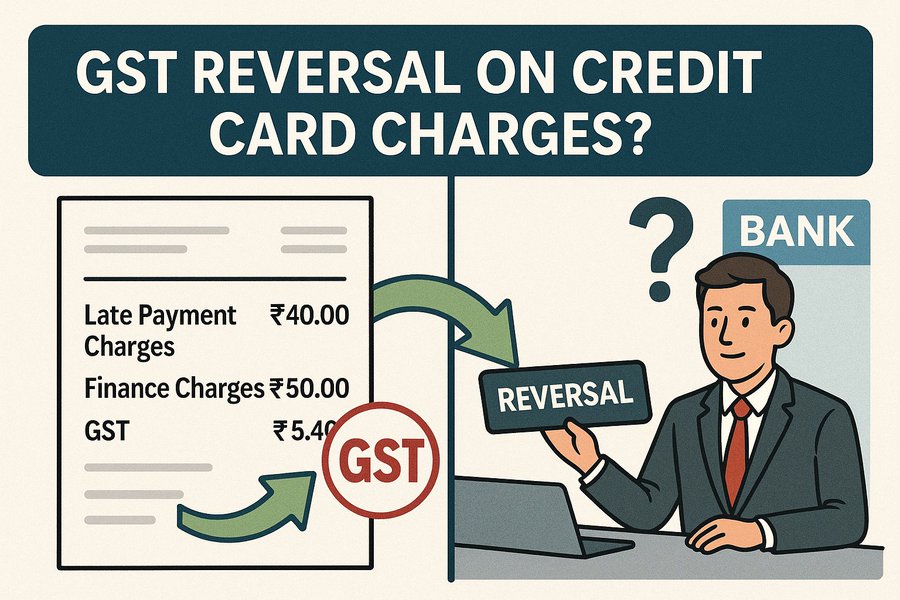
The implementation of the Goods and Services Tax (GST) in India from July 1, 2017, marked a significant transformation of the country’s indirect tax structure. Banking and financial services, given their complexity and diverse offerings, presented unique challenges within this framework. A recurring point of contention arises when banks reverse charges such as late payment fees or finance charges along with the applicable GST. This analysis explores the legal obligations surrounding GST reversal when banks reverse underlying charges, focusing on the procedures mandated under the Central Goods and Services Tax Act, 2017 (CGST Act).
GST Applicability on Bank Charges
Legal Basis for Taxation
The foundation for levying GST on bank charges stems from the definition of ‘value of supply’ under the CGST Act. Section 15(2)(d) explicitly states that the value of supply includes “interest or late fee or penalty for delayed payment of any consideration for any supply.” When a bank provides a service, additional amounts charged due to the customer’s delay in fulfilling payment obligations are considered part of the value of the underlying banking service and are brought within the scope of GST levy.
Financial services predominantly fall under Service Accounting Code (SAC) 9971. Most ancillary banking services that involve explicit fees attract GST at the standard rate of 18% (levied as 9% CGST + 9% SGST for intra-state supplies or 18% IGST for inter-state supplies). This includes late payment charges, finance charges on credit cards, processing fees, annual fees, and similar levies.
Distinguishing Taxable Charges from Exempt Interest
It’s crucial to differentiate between taxable charges and exempt interest components. Notification No. 12/2017-Central Tax (Rate), dated June 28, 2017, provides an exemption for “services by way of extending deposits, loans or advances in so far as the consideration is represented by way of interest or discount.” This exemption covers interest earned by banks on standard loans and advances and interest paid on deposits.
However, this exemption explicitly excludes “interest involved in credit card services.” This exclusion confirms that interest charged on outstanding credit card balances, often referred to as finance charges, is liable to GST at 18%. Furthermore, official FAQs clarify that any additional interest or penal interest charged for default in payment of installments related to a supply which is itself subject to GST, is includible in the value of that supply and hence liable to GST.
The Emergence of ‘Penal Charges’
A significant development occurred following a directive from the Reserve Bank of India (RBI) issued in August 2023. This directive mandated Regulated Entities (REs), including banks, to replace ‘penal interest’ with ‘penal charges’ for non-compliance with material loan terms and conditions. These penal charges are to be levied reasonably and non-discriminatorily on the defaulted amount only and should not be capitalized.
Subsequently, the Central Board of Indirect Taxes and Customs (CBIC) issued Circular No. 245/02/2025-GST, dated January 28, 2025, clarifying that these specific ‘penal charges’ are not subject to GST. The rationale provided is that such charges are akin to damages or penalties for breach of contract terms, rather than constituting consideration for a supply of service.
This creates a critical distinction in GST treatment based on the nature and timing of the charge:
‘Late payment fees’, ‘finance charges’ (especially on credit cards), and ‘penal interest’ levied prior to the RBI directive’s implementation generally remain taxable under Section 15(2)(d).
‘Penal charges’ levied strictly in accordance with the RBI’s August 2023 guidelines are exempt from GST.
GST Adjustment Mechanism for Reversed Charges
Credit Notes Under Section 34, CGST Act
When a bank reverses a previously levied taxable charge, this action effectively constitutes a reduction in the value of the service originally supplied. The CGST Act provides a specific legal instrument to handle such situations: Credit Notes, as defined under Section 34.
Section 34(1) outlines the circumstances requiring a registered person to issue credit notes:
When the taxable value charged exceeds the actual taxable value payable
When the tax charged exceeds the actual tax payable
When goods supplied are returned
When goods or services supplied are found deficient
The reversal of a taxable bank charge clearly falls under conditions (1) and (2). If a late payment fee was charged and later waived, the taxable value and tax originally charged exceed the final amount payable, statutorily triggering the requirement for the bank to issue a credit note under Section 34(1).
Procedural Requirements and Timelines
The bank must declare credit note details in their GST return (Form GSTR-1) for the month of issuance. There is a statutory time limit for declaring these credit notes for adjusting tax liability – no later than the 30th day of November following the end of the financial year in which the original supply was made, or the date of furnishing the relevant annual return (Form GSTR-9), whichever is earlier.
Rule 53(1A) of the CGST Rules, 2017 prescribes the specific particulars that must be contained in a credit note, including supplier and recipient details, unique serial number, date of issue, reference to the corresponding original tax invoice(s), value of supply, rate of tax, and the amount of tax credited.
No tax without transaction
Some banks may assert that “the GST component once charged will not be reversed” despite reversing the associated service fees is contrary to established GST law and is legally untenable. As per Section 34(1) of the CGST Act, 2017, the issuance of a credit note is mandatory when the taxable value of a supply decreases. The use of the word “shall” indicates a statutory obligation, not discretion.
Retaining the GST component after reversing the service charge amounts to collecting tax without an underlying supply, violating the fundamental principle of “no tax without transaction.” It either results in wrongful retention of funds belonging to the government or to the customer and creates inconsistencies in tax accounting.
Under Section 9 of the CGST Act, banks(or any other service provider) act merely as a conduit for tax collection and not as a beneficiary. GST collected on a reversed transaction is not banks revenue. Retaining it amounts to unjust enrichment, and may be in violation of Section 171.
Bnaks position also exposes banks to regulatory risk, including penalties under Section 122 for incorrect invoicing, interest under Section 50 for excess tax collection, and even prosecution under Section 132. Additionally, banks may be subject to consumer claims for systematic overcharging and unfair trade practices.
Further, CBIC Circular No. 137/07/2020-GST makes it clear that changes in consideration must be accompanied by corresponding tax adjustments. Although the circular addresses construction services, the principle applies broadly to all taxable services.
Banks are also legally obligated to issue a proper credit note detailing the original invoice reference, the decreased taxable value, the corresponding tax amount (CGST, SGST/UTGST, or IGST), and the reason—specifically, “Reversal of service charges.”
The Critical Link: Recipient’s Input Tax Credit (ITC) Reversal
A pivotal change was recommended by the 55th GST Council meeting in December 2024 and subsequently proposed for legislative amendment. This amendment to Section 34(2) introduces a critical condition for the supplier’s reduction of output tax liability.
The new requirement stipulates that a supplier (bank) issuing a credit note can reduce their output tax liability only if the recipient of the supply (the customer) has reversed the Input Tax Credit (ITC) that corresponds to the reduction in value specified in the credit note.
The objective of this amendment is to plug a potential revenue leakage loophole. Previously, a supplier could issue a credit note and reduce their tax liability, while the recipient might fail to reverse the corresponding ITC they had claimed based on the original invoice.
This amendment significantly alters the operational dynamics and compliance burden. It places the onus on the bank not only to issue the credit note but also to ensure that the recipient has performed the corresponding ITC reversal before the bank can legitimately reduce its own tax payment. Obtaining such confirmation presents a considerable operational challenge, which may explain banks’ reluctance or delay in reversing the GST component of charges.
Practical Scenarios
Scenario 1: Late Payment Fee Reversed (B2B)
When a business customer (registered under GST) is charged a late payment fee plus GST on their corporate credit card and subsequently gets it reversed:
Bank’s Action:
Reverse the base charge
Issue a GST Credit Note for the taxable value reduction and tax reduction
Inform the business customer about their obligation to reverse the ITC previously claimed
Obtain confirmation from the business that they have reversed the ITC
Declare the Credit Note details in the bank’s GSTR-1
Only after receiving confirmation of ITC reversal, reduce its output tax liability
Customer’s Action:
Receive the Credit Note
Reverse the ITC claimed earlier in their GSTR-3B
Confirm the reversal to the bank
Scenario 2: Finance Charge Reversed (B2C)
When an individual (unregistered customer) is charged finance charges plus GST on their personal credit card and gets it reversed:
Bank’s Action:
Reverse the base charge
Issue a financial credit note documenting the reversal of the charge plus GST
Declare the details of this reduction in their GSTR-1
Reduce its output tax liability in its GSTR-3B
Customer’s Action:
The customer, being unregistered, cannot claim ITC. Therefore, the requirement for ITC reversal does not apply
The customer simply benefits from the total reversal
Impact of Amended Section 34(2) on Compliance
The requirement for banks to ensure recipient ITC reversal before adjusting their own liability presents significant practical hurdles:
Communication & Coordination: Banks need robust systems to communicate the issuance of credit notes and the recipient’s obligation to reverse ITC.
Verification: Establishing a reliable mechanism to verify that the recipient has actually reversed the ITC is difficult. Relying solely on customer confirmation might be risky from an audit perspective.
Timelines: Delays in recipient confirmation could push the bank beyond the November 30th deadline for adjusting its tax liability, leading to a permanent loss of the tax amount for the bank.
Disputes: If a customer disputes the need to reverse ITC or fails to do so, the bank is caught in the middle, unable to reduce its liability despite having reversed the charge.
This increased compliance burden might lead banks to be more cautious or slower in processing GST reversals accompanying charge reversals, potentially explaining observed delays in the system.
Official Clarifications and Jurisprudence
While specific circulars addressing the reversal of general bank charges seem scarce, the foundational principles are well-established:
Taxability of Charges: FAQs and rate notifications confirm the taxability of late fees and credit card interest under SAC 9971 at 18%.
Credit Note Mechanism: Section 34 and associated rules provide the general framework, with the recent amendment tightening the link to recipient ITC reversal.
Penal Charges Exemption: Circular No. 245/02/2025-GST clarifies the exemption for specific penal charges mandated by RBI, distinguishing them from taxable late fees/interest.
Advance Rulings consistently uphold the taxability of ancillary bank charges. For instance:
Re: Bajaj Finance Ltd. (Maharashtra AAR): Confirmed GST applicability on various penal and additional interest charges levied on customers for delayed EMI payments.
Re: Cholamandalam Investment and Finance Company Ltd. (Tamil Nadu AAR): Held that additional/penal interest on delayed loan installments is part of the value of supply and taxable.
Conclusion
When banks reverse late payment charges or finance charges that were originally subject to GST, they are legally obligated under Section 34 of the CGST Act to also reverse the GST component collected on those charges by issuing a GST Credit Note to the customer.
However, the bank’s ability to reduce its own tax payment to the government based on this credit note is now contingent upon the registered customer reversing the corresponding Input Tax Credit. This recent amendment introduces a procedural complexity that may cause delays or require active participation from the customer (in B2B cases). For unregistered (B2C) customers, the bank can directly adjust its liability after issuing the credit note and reporting it.
Despite practical difficulties, the legal obligation under Section 34 remains. Any systemic refusal by banks to reverse GST alongside the base charge would likely be contrary to Section 34 and potentially challengeable. The operational difficulty introduced by the amended Section 34(2) may explain practical delays but does not extinguish the fundamental legal obligation.
Recommendations
For Banks:
Implement clear internal procedures for issuing GST Credit Notes whenever taxable charges are reversed
Develop robust communication channels to inform B2B customers about issued Credit Notes
Explore mechanisms to obtain confirmation of ITC reversal
Ensure timely reporting of Credit Notes in GSTR-1
Clearly differentiate between taxable charges and exempt charges
For Customers (Businesses):
Be aware that if a bank reverses a charge on which you claimed ITC, you are obligated to reverse that ITC
Expect to receive a GST Credit Note for reversed taxable charges
Cooperate with the bank by confirming ITC reversal promptly
Escalate matters if a bank refuses to issue a GST Credit Note for the tax component
For Policymakers (GST Council/CBIC):
Consider issuing further clarifications addressing the operational challenges arising from the amended Section 34(2)
Enhance GSTN portal functionalities to facilitate easier matching and confirmation of credit notes and corresponding ITC reversals
References
Central Goods and Services Tax Act, 2017, Section 15.
Notification No. 12/2017-Central Tax (Rate), dated June 28, 2017.
CBIC, “FAQ on Banking, Insurance and Stock Brokers Sector.”
ClearTax, “GST on Banking Sector: Impact & Important Provisions.”
BankBazaar, “GST on banking and financial services: Applicability, rates and more.”
Masters India, “Impact of GST on Banking Sector.”
Notification No. 11/2017-Central Tax (Rate), dated June 28, 2017.
Bajaj Finserv Markets, “GST on Credit Card Transactions: Fees, Charges, Benefits, and More.”
CBIC, “FAQ on Financial Services Sector.”
SAG Infotech, “GST On Banking Services: Latest News and Impact.”
Financial Express, “GST impact on banking services: Here’s the list of transactions to become costlier from July 1,” June 2017.
RBI Circular: DOR.STR.REC.50/21.04.048/2023-24, dated August 18, 2023 – Fair Lending Practice – Penal Charges in Loan Accounts.
CBIC Circular No. 245/02/2025-GST, dated January 28, 2025.
Press Release: Recommendations of 55th GST Council Meeting, dated December 21, 2024.
Business Standard, “GST Council decides penal charges by banks won’t attract GST,” Dec 2024/Jan 2025.
CBIC Circular No. 178/10/2022-GST, dated August 3, 2022.
ICICI Bank, “GST on Loan: Processing Fee, Interest Rates, EMI.”
Central Goods and Services Tax Act, 2017, Section 34.
Arbitration has become a cornerstone of dispute resolution in India, prized for its flexibility and efficiency in handling commercial conflicts. Yet, a subtle but critical detail often escapes attention: the governing law of the arbitration agreement. This law shapes the agreement’s validity, scope, and enforceability. A recent legislative shift in the United Kingdom, overturning the Enka v Chubb ruling, has sparked fresh debate on this topic. What does this change mean for India, a nation with its own evolving arbitration landscape? This article explores the UK’s amendment, contrasts it with Indian judicial approaches, and considers its implications for Indian arbitration.
The UK’s Legislative Shift: From Enka v Chubb to Section 6A
In the UK, the case of Enka Insaat VF Sanayi AS v. OOO Insurance Co. Chubb established a structured method to identify the governing law of arbitration agreements when parties didn’t explicitly choose one. Drawing from the earlier Sulamerica case, it outlined a three-step process:
Express Choice: Check if the parties explicitly selected a governing law for the arbitration agreement.
Implied Choice: If no express choice exists, assume the law of the main contract applies, as the arbitration clause is embedded within it.
Closest Connection: If applying the main contract’s law undermines the arbitration agreement, default to the law of the seat, deemed the most closely connected.
This approach balanced party autonomy with practicality. However, the UK Parliament recently amended the English Arbitration Act, 1996, introducing Section 6A via the English Arbitration Act, 2025. This new provision simplifies the process: the governing law is what the parties expressly agree on, or, absent such agreement, the law of the seat applies. The change reflects trade practices where parties often specify a seat but not a separate governing law for the arbitration clause, aiming to enhance legal certainty.
India’s Evolving Stance on Governing Law
Indian courts have grappled with similar questions, producing a patchwork of precedents. Early on, in National Thermal Power Corp v. Singer Co. [(1992) 3 SCC 551], the Supreme Court ruled that the proper law of the contract governs the arbitration agreement unless the parties state otherwise. This mirrored the Sulamerica logic, prioritizing the main contract’s law.
A shift came in 2012 with BALCO v. Kaiser Aluminium Technical Services Inc. [(2012) 9 SCC 552]. A Constitution Bench held that choosing India as the seat of arbitration triggers Part I of the Arbitration and Conciliation Act, 1996, automatically applying Indian law to the arbitration agreement. This seat-centric view suggested a departure from the earlier approach, aligning with practical considerations in international arbitration.
Yet, clarity proved elusive. In 2023, a three-judge bench in Disortho SAS v. Meril Life Sciences Private Limited revisited the issue, reaffirming the Sulamerica three-step test. It ruled that absent an express choice, the proper law of the contract governs, citing consistency with Enka. Despite referencing BALCO, the decision leaned toward pre-BALCO principles, leaving practitioners questioning whether India favors a seat-based or contract-based default.
Should India Emulate the UK?
The UK’s shift to a seat-centric default offers appealing simplicity. By tying the governing law to the seat unless specified otherwise, it reduces ambiguity—a boon for international trade where seat designation is common. The English Law Commission, in its Final Report, argued this aligns with party intent and market norms, dismissing the Enka test’s reliance on implied choice as overly complex.
For India, however, the picture is murkier. A key hurdle is the unresolved debate over determining the seat when it’s not explicitly stated. In Union of India v. Hardy Exploration and Production (India) INC [(2018) 7 SCC 374], the Supreme Court held that a venue doesn’t automatically become the seat without additional indicators—like the arbitration’s legal or procedural context. Conversely, BGS SGS SOMA JV v. NHPC Ltd. [(2020) 4 SCC 234] ruled that the venue is the seat unless the contract suggests otherwise. These conflicting rulings from co-equal benches muddy the waters, making a seat-centric default riskier in India than in the UK.
An Expert Committee tasked with reforming the Arbitration and Conciliation Act, 1996 proposed embedding the term “seat” in sections like 2(2) and 20 to clarify its role. Yet, it sidestepped the Hardy–BGS conflict, leaving the issue dangling. Adopting the UK’s model now could amplify confusion rather than resolve it, as parties might litigate the seat’s identity before even addressing the governing law.
A Path Forward for India
Given these challenges, India might fare better by retaining its current approach—at least for now. The Disortho ruling, echoing Enka and Sulamerica, provides a workable framework: prioritize express choice, then the proper law, and adjust if necessary. This avoids over-reliance on a seat that Indian courts can’t consistently define.
Still, the UK’s amendment offers a lesson in proactive clarity. India could eventually adopt a similar rule, but only after settling the seat-determination debate through legislation or a larger Supreme Court bench. Meanwhile, the onus falls on parties drafting contracts. Explicitly stating both the governing law and the seat—ideally in the arbitration clause itself—can preempt disputes, saving time and costs.
Conclusion
The UK’s legislative overruling of Enka v Chubb underscores the value of certainty in arbitration, a goal India shares but struggles to achieve amid judicial inconsistencies. While the seat-centric approach suits the UK’s trade-driven context, India’s arbitration ecosystem demands caution. Sticking with the Disortho framework makes sense until the seat conundrum is resolved. For businesses and legal practitioners, the takeaway is clear: spell out your choices in the contract. In arbitration, as in life, precision today prevents headaches tomorrow.
References
National Thermal Power Corp v. Singer Co., (1992) 3 SCC 551
BALCO v. Kaiser Aluminium Technical Services Inc., (2012) 9 SCC 552
Disortho SAS v. Meril Life Sciences Private Limited, (2023) [Supreme Court of India, exact citation pending]
Union of India v. Hardy Exploration and Production (India) INC, (2018) 7 SCC 374
BGS SGS SOMA JV v. NHPC Ltd., (2020) 4 SCC 234
Arbitration and Conciliation Act, 1996, Government of India
India’s labour law framework has undergone a historic transformation with the codification of 29 central labour laws into four comprehensive codes: the Code on Wages, 2019, the Industrial Relations Code, 2020, the Code on Social Security, 2020, and the Occupational Safety, Health and Working Conditions (OSHWC) Code, 2020. These reforms aim to streamline a historically complex and fragmented regulatory system, enhance the Ease of Doing Business (EoDB), foster industrial flexibility, and extend protections to India’s vast unorganized workforce, which comprises over 90% of the labour force—approximately 500 million workers. This article provides an in-depth analysis of the reforms’ objectives, provisions, potential benefits, challenges, and international lessons, concluding with actionable recommendations to ensure their successful implementation.
The Imperative for Reform: Unraveling a Legacy System
A Labyrinth of Laws
Prior to the codification, India’s labour regulatory landscape was a patchwork of over 40 central and 100 state laws, many dating back to the colonial era, such as the Factories Act (1881, revised 1948) and the Mines Act (1901, revised 1952). This multiplicity created overlapping jurisdictions, inconsistent definitions (e.g., “wages,” “employee,” “establishment”), and significant compliance burdens, particularly for Micro, Small, and Medium Enterprises (MSMEs). For instance, the Industrial Disputes Act (IDA), 1947, required government approval for layoffs, retrenchment, or closures in firms with 100 or more workers, a provision widely criticized by industry for stifling flexibility. This rigidity was believed to encourage firms to remain small (a phenomenon termed “dwarfism”), rely heavily on contract labour, or adopt capital-intensive technologies to avoid regulatory thresholds.
The complexity was compounded by definitional inconsistencies across statutes, leading to legal ambiguity and disputes. Businesses operating across states faced a patchwork of compliance requirements, disproportionately affecting MSMEs, which often lacked the resources for legal expertise. Larger corporations, with dedicated legal teams, navigated the system more easily, highlighting an uneven playing field that hindered economic scalability and formalization.
Exclusion of the Informal Workforce
A defining flaw of the pre-reform system was its limited reach, covering primarily the organized sector (less than 10% of the workforce). The Periodic Labour Force Survey (PLFS) 2022-23 estimated over 465 million informal workers, many earning below ₹5,000/month, with 27.5% earning less than ₹3,000/month according to PLFS 2023-24. These workers—spanning agriculture, small enterprises, home-based work, and casual labour—were largely excluded from statutory protections like minimum wages, social security (e.g., provident fund, insurance), or workplace safety standards. This exclusion perpetuated a dualistic labour market: a small, protected formal sector and a vast, precarious informal sector.
The vulnerability of informal workers was starkly exposed during the COVID-19 pandemic, particularly among inter-state migrant workers (ISMWs). The lack of portable benefits and social safety nets led to significant distress, with reports documenting 972 deaths during reverse migration. This crisis underscored the urgent need for a more inclusive labour framework that addresses the needs of India’s informal majority.
Economic and Governance Drivers
The reforms were propelled by India’s ambition to climb the World Bank’s EoDB rankings, attract foreign and domestic investment, and align with national initiatives like “Make in India,” “Digital India,” and “Startup India.” The government’s “Minimum Government, Maximum Governance” philosophy emphasized reducing bureaucratic hurdles, streamlining regulations, and leveraging technology, such as the e-Shram portal for worker registration. Simultaneously, the reforms aimed to achieve social justice by extending protections to informal, gig, and platform workers, aligning with the Second National Commission on Labour (SNCL) recommendations for consolidating laws into thematic codes.
The dual objectives—enhancing business ease and expanding worker welfare—reflect a philosophical shift from a fragmented, protectionist model to one aiming for universal applicability, simplification, and a balance between market-driven flexibility and baseline protections. This ambitious undertaking seeks to modernize India’s labour governance to support its goal of becoming a $5 trillion economy while addressing deep-rooted inequities.
The Four Labour Codes: A Detailed Examination
1. Code on Wages, 2019: Universalizing Wage Protections
Objective and Scope: Enacted in August 2019, the Code on Wages consolidates four laws: the Payment of Wages Act, 1936, Minimum Wages Act, 1948, Payment of Bonus Act, 1965, and Equal Remuneration Act, 1976. It aims to universalize minimum wage entitlements, ensure timely payments, standardize wage definitions, and promote gender equity across all sectors.
Key Provisions:
Unified Wage Definition: Defines “wages” as basic pay, dearness allowance, and retaining allowance, capping exclusions (e.g., bonuses, PF contributions, overtime) at 50% of total remuneration to prevent artificial wage suppression for statutory dues like provident fund and gratuity.
National Floor Wage: Empowers the central government to set a baseline wage, considering living standards (e.g., food, housing, clothing for a family of three). States must set minimum wages above this floor, reducing regional disparities.
Gender Equity: Prohibits wage discrimination based on gender for similar work, aligning with ILO Convention No. 100.
Compliance Simplification: Reduces paperwork, mandates electronic wage payments, and caps permissible deductions at 50% of wages.
Overtime and Bonus: Ensures overtime wages at twice the normal rate and a minimum bonus of 8.33% of annual wages for eligible employees.
Socio-Economic Context: PLFS data highlights severe wage challenges: 53.5% of workers earn below the MNREGS benchmark (~₹9,000/month), and women face a 20–33% gender wage gap. Rural-urban disparities are significant, with urban wages often double rural ones. The national floor wage aims to address these issues, but its impact depends on setting an adequately high level and robust enforcement, particularly in the informal sector where compliance is historically weak.
Potential Impact: The code could uplift millions of low-wage workers, reduce gender and regional disparities, and simplify employer compliance. However, challenges include potential state resistance to high floor wages due to investment competitiveness, ambiguity in calculating the 50% exclusion cap, and enforcement gaps in unregistered enterprises.
2. Industrial Relations Code, 2020: Balancing Flexibility and Harmony
Objective and Scope: Enacted in September 2020, this code consolidates the Trade Unions Act, 1926, Industrial Employment (Standing Orders) Act, 1946, and IDA, 1947. It seeks to streamline dispute resolution, enhance labour market flexibility, formalize trade union recognition, and promote industrial peace.
Key Provisions:
Retrenchment Threshold: Raises the limit for government approval for layoffs, retrenchment, or closures from 100 to 300 workers, easing flexibility for mid-sized firms.
Fixed-Term Employment (FTE): Legalizes FTE across industries, granting pro-rata benefits (e.g., PF, ESI) but excluding contract expiry from retrenchment protections, potentially increasing precariousness.
Trade Union Recognition: Designates a union with 51% worker support as the Sole Negotiating Union or forms a Negotiating Council for unions with 20%+ support, aiming to streamline bargaining.
Worker Re-skilling Fund: Employers contribute 15 days’ wages per retrenched worker to fund retraining.
Strike Regulations: Extends the mandatory notice period for strikes to 14 days for all establishments and classifies mass casual leave by 50%+ workers as a strike.
Case Study: Rajasthan’s Reforms: Rajasthan’s 2014 increase in the retrenchment threshold to 300 workers offers insights. An NIPFP study noted a 12% employment increase in large firms, but other analyses, like Goswami and Paul (2020), found increased contract labour and reduced overall labour use in export-oriented firms. Goldar (2024) argued that relaxed regulations boosted manufacturing jobs, illustrating mixed outcomes.
Stakeholder Perspectives: Industry welcomes the flexibility, citing reduced exit barriers. However, trade unions criticize the weakened job security for workers in firms with 100–300 employees and the potential for FTE to create “permanently temporary” roles. The decline in union density (from 19% in 1993 to 12.5% in 2014, per ILO estimates) raises concerns about diminished collective bargaining power.
Potential Impact: The code could stimulate formal sector hiring by reducing regulatory barriers, but risks exacerbating labour market dualism, with stronger protections for large-firm workers and increased precarity for others. The Worker Re-skilling Fund is promising but requires robust administration to align training with market needs, given past challenges with initiatives like Skill India.
3. Code on Social Security, 2020: Extending the Safety Net
Objective and Scope: Enacted in September 2020, this code consolidates nine laws, including the Employees’ Provident Funds Act, 1952, Employees’ State Insurance Act, 1948, and Unorganised Workers’ Social Security Act, 2008. It aims to universalize social security, notably including gig and platform workers for the first time.
Key Provisions:
Gig/Platform Worker Inclusion: Defines gig workers (freelancers outside traditional employment) and platform workers (engaged via online platforms like Uber, Zomato). NITI Aayog estimates 7.7 million such workers in 2020-21, projected to reach 23.5 million by 2029-30.
e-Shram Portal: A national database with over 300 million registered unorganized workers, providing a Universal Account Number (UAN) for accessing benefits like health, maternity, and pensions.
Social Security Funds: Central fund for gig/platform workers and state funds for unorganized workers, partially funded by a 1–2% aggregator levy (capped at 5% of payouts).
Mandatory Registration: Workers register via e-Shram, with Aadhaar mandatory for benefit access.
Socio-Economic Context: The gig economy’s rapid growth underscores the code’s relevance. These workers face income instability, no minimum wage guarantees, and exclusion from traditional benefits. Women, constituting 53.68% of e-Shram registrations, are particularly vulnerable to low earnings (e.g., rural self-employed women earn ~₹5,000/month).
Case Study: Karnataka’s Gig Worker Bill: Karnataka’s 2024 draft bill mandates a 1–2% welfare levy on aggregators, offering a state-level model. However, debates over turnover definitions and compliance complexity highlight challenges scalable to the national level.
Potential Impact: The code’s inclusion of gig workers is groundbreaking, but funding adequacy is a concern. The FY 2023-24 allocation of ₹350 crore is dwarfed by the target population’s scale. The Union Budget 2025-26’s expansion of PMJAY health coverage to 10 million gig workers is a step forward, but sustainable financing remains unresolved. Administrative integration across states and portability of benefits are critical for success.
4. Occupational Safety, Health and Working Conditions (OSHWC) Code, 2020
Objective and Scope: Enacted in September 2020, this code consolidates 13 laws, including the Factories Act, 1948, Mines Act, 1952, and Inter-State Migrant Workmen Act, 1979. It aims to enhance workplace safety, health, and conditions across establishments with 10+ workers.
Key Provisions:
Employer Duties: Mandates hazard-free workplaces, free annual health check-ups for hazardous sectors, and welfare facilities (e.g., canteens, crèches).
Appointment Letters: Requires formal letters for all employees, promoting formalization.
Inspector-cum-Facilitator: Shifts to a facilitative enforcement model with web-based, risk-based inspections.
Ground Reality: A CAG 2022 report found only 35% of factories fully compliant with safety norms. High-risk sectors like construction and sanitation, employing over 60% of workers, face elevated morbidity. Sanitation workers, often from marginalized castes, face extreme hazards, with an estimated 2 million in high-risk roles.
Case Study: Migrant Worker Crisis: The COVID-19 lockdowns exposed ISMW vulnerabilities, with millions stranded without support. The code’s portability provisions are a response, but effective inter-state coordination remains a hurdle.
Potential Impact: The code strengthens safety standards and formalization, but its 10-worker threshold excludes micro-enterprises, a significant informal sector segment. Enforcement capacity and digital infrastructure are critical for realizing benefits.
Potential Benefits of the Reforms
Simplified Compliance: Consolidating 29 laws into four reduces administrative burdens, potentially lowering compliance costs by 20–30% for MSMEs, per industry estimates.
Economic Growth: Enhanced flexibility and EoDB could attract FDI, supporting “Make in India” and manufacturing growth.
Social Inclusion: Universal minimum wages and social security for informal workers could reduce poverty and inequality.
Formalization and Digitization: Mandatory appointment letters and e-Shram registration promote formal employment, with over 30 crore workers already registered.
Implementation Challenges
1. Centre-State Harmonization
Labour’s Concurrent List status requires states to align rules with central codes. As of early 2025, 24–31 states/UTs have drafted rules, targeting finalization by March 31, 2025. Variations could recreate fragmentation, undermining the codes’ uniformity goal. Political differences across states add complexity.
2. Enforcement Capacity
The Inspector-cum-Facilitator model requires retraining thousands of officials and robust digital platforms. Historical enforcement weaknesses, especially in the informal sector, risk undermining compliance. The V.V. Giri National Labour Institute’s training programs are a start, but scaling is essential.
3. Funding Gaps
The Code on Social Security’s universalization ambition lacks clear financing. The 1–2% aggregator levy is debated for sufficiency, and FY 2023-24’s ₹350 crore allocation is inadequate for millions of workers. International models (e.g., US Social Security’s 12.4% payroll contribution) suggest higher, tripartite contributions.
4. Worker Rights Concerns
Increased retrenchment flexibility and FTE may weaken job security, particularly for workers in firms with 100–300 employees. Stricter strike rules and union recognition thresholds could reduce collective bargaining power, with union density already low at 7‒12.5%.
5. Digital and Administrative Integration
The e-Shram portal’s success depends on data accuracy, accessibility, and interoperability with state systems. Ensuring benefit portability (e.g., PDS, ESI, EPF) across states requires overcoming technological and governance barriers.
International Lessons: Pathways and Pitfalls
Indonesia’s Omnibus Law (2020)
Indonesia’s law aimed to simplify regulations and attract FDI but faced backlash for prioritizing flexibility (e.g., easier terminations, reduced severance) over worker rights. The Constitutional Court’s 2021 ruling declared it “conditionally unconstitutional” due to inadequate public consultation, forcing revisions. Lesson: Robust social dialogue is critical to avoid resistance and ensure legitimacy.
Brazil’s Labour Reform (2017)
Brazil’s reform liberalized outsourcing and introduced flexible contracts, aiming to boost jobs. However, it increased precariousness, reduced real wages, and weakened unions, with no significant formal employment growth. Lesson: Flexibility without strong social protections can exacerbate inequality and dual labour markets.
Vietnam’s Social Protection Expansion (2012–2020)
Vietnam achieved high health insurance coverage through mandatory contributions, state subsidies, and scheme integration. Challenges persisted in reaching informal workers, but political commitment drove success. Lesson: Sustainable financing and phased implementation are key to universal coverage.
Recommendations for Effective Implementation
National Labour Code Implementation Council Establish a council with Central, State, employer, and worker representatives to harmonize rules, resolve disputes, and monitor implementation. It should operate as a permanent body, adapting rules based on feedback and emerging labour market trends. Example: The council could mediate state variations in minimum wage fixation to ensure national coherence.
Labour Law Facilitation Cells for MSMEs Create cells via SIDBI and NSIC to provide MSMEs with compliance support, including workshops, helplines, templates, and compliance software. These cells should integrate business development advice, helping MSMEs leverage flexibility provisions (e.g., FTE) strategically. Example: SIDBI’s existing MSME financing network could host regional compliance clinics.
₹5,000 Crore Social Security Transition Fund Seed a fund to kickstart social security schemes, matching state contributions and co-funding aggregator levies. Governance should ensure transparency and alignment with long-term financing (e.g., payroll-based contributions). Example: The fund could finance e-Shram enrollment drives and initial health insurance for gig workers.
Capacity Building and Digital Infrastructure Invest in training Inspector-cum-Facilitators for advisory roles and scaling digital platforms like e-Shram. Develop mobile apps for worker redressal and interoperable databases for benefit portability. Example: Partner with tech firms to enhance e-Shram’s user interface and data security.
Staggered Rollout Strategy Implement codes in phases, starting with Wages and Social Security, and by firm size (large → medium → small) over three years. Clear timelines and support mechanisms (e.g., MSME cells) are crucial to minimize disruption. Example: Pilot implementation in urban industrial clusters before rural rollout.
Stakeholder Engagement and Awareness Launch nationwide campaigns to educate employers, workers, and unions about their rights and obligations. Engage trade unions in rule-making to build trust and reduce resistance. Example: Use media and community organizations to promote e-Shram registration among rural workers.
Conclusion: From Vision to Reality
India’s Labour Code reforms are a landmark effort to modernize a fragmented system, aligning labour governance with economic aspirations and social equity goals. By simplifying compliance, enhancing flexibility, and extending protections to informal and gig workers, the codes promise to transform India’s labour market. However, their success depends on overcoming significant challenges: harmonizing Centre-State rules, strengthening enforcement, securing sustainable funding, and balancing flexibility with worker rights.
International experiences—Indonesia’s cautionary tale, Brazil’s mixed outcomes, and Vietnam’s success—offer valuable lessons. The recommended strategies—a National Implementation Council, MSME facilitation, a transition fund, capacity building, staggered rollout, and stakeholder engagement—provide a roadmap for effective realization. With sustained political will, administrative diligence, and inclusive dialogue, India can translate these legislative promises into a dynamic, equitable labour market that supports its vision of inclusive growth and global economic leadership.
References
India’s New Labor Codes Enactment Status and Delayed Implementation, accessed May 4, 2025.
REFORM AND CODIFICATION OF India’s Labour Laws, cloudfront.net, accessed May 4, 2025.
Overview of Labour Law Reforms, PRS India, accessed May 4, 2025.
Changing Paradigm of the Labour Laws in India: A legal Analysis, ResearchGate, accessed May 4, 2025.
The Code on Wages, 2019, PRS India, accessed May 4, 2025.
The Industrial Relations Code, 2020, PRS India, accessed May 4, 2025.
The Code on Social Security, 2020, PRS India, accessed May 4, 2025.
The Occupational Safety, Health and Working Conditions Code, 2020, PRS India, accessed May 4, 2025.
Impact of Labour Reforms on Industry in Rajasthan, PHD Chamber, accessed May 4, 2025.
India’s Booming Gig and Platform Economy, NITI Aayog, accessed May 4, 2025.
E-Shram: One Stop Solution for Unorganised Workers, PIB, accessed May 4, 2025.
Indian States, UTs to Finalize Labor Codes Rules by March 2025, India Briefing, accessed May 4, 2025.
Indonesia’s Omnibus Law on Job Creation, Hogan Lovells, accessed May 4, 2025.
Brazil’s Labor Reform: How It’s Impacting the Job Market, Global People Strategist, accessed May 4, 2025.
Integrating Social Health Protection Systems Lessons Learned, accessed May 4, 2025.
3 in 4 Indian Labourers Earn Less Than Rs 15,000 A Month, Outlook Business, accessed May 4, 2025.
Article 254 of the Constitution of India stands as the cornerstone provision for addressing and resolving inconsistencies that arise between laws enacted by the Parliament of India (Union legislature) and those enacted by the Legislatures of the States.1 Its existence is fundamental within India’s constitutional architecture, often characterized as ‘quasi-federal’.3 This characterization stems from a structure that, while dividing powers between the Union and the States, also establishes significant areas of shared legislative authority and retains certain centralizing features.5 Article 254 provides the specific mechanism to manage conflicts within this framework, particularly in the domain where both levels of government are competent to legislate.6 The provision finds its roots in Section 107 of the Government of India Act, 1935, indicating a continuity in addressing legislative overlap from the pre-Independence era.6
The very presence and detailed nature of Article 254 underscore the foresight of the Constitution’s framers. They anticipated the potential for considerable legislative friction, especially concerning subjects placed in the Concurrent List of the Seventh Schedule.8 The Constitution meticulously delineates legislative powers through Article 246 and the three lists in the Seventh Schedule – the Union List, the State List, and the Concurrent List.11 The deliberate inclusion of a substantial Concurrent List, granting simultaneous legislative power to both the Union and the States over numerous important subjects 10, inherently created a zone of potential conflict. Article 254 was thus not an incidental provision but a carefully designed instrument to regulate this anticipated overlap.1 It establishes a clear, albeit complex, hierarchy and procedure for resolving conflicts, aiming to balance the need for national uniformity with the space for state-level legislative action within the quasi-federal structure.3 The nuanced exception provided in clause (2) further suggests a sophisticated approach beyond simple central dominance.
2/3 Significance in Concurrent Legislation
The primary operational sphere of Article 254 is the Concurrent List (List III of the Seventh Schedule).1 This list enumerates subjects upon which both Parliament and State Legislatures are competent to make laws.8 The rationale for a concurrent list includes the need for uniformity in basic laws across the country while allowing for state-specific variations where necessary. However, this shared legislative space inevitably leads to situations where a law made by a State Legislature may conflict with a law made by Parliament on the same subject. Article 254 provides the constitutional rule to determine which law prevails in such instances.7
It is crucial to distinguish conflicts under Article 254 from issues of legislative competence. If Parliament legislates on a matter exclusively reserved for the States (List II), or a State legislates on a matter exclusively reserved for the Union (List I), the resulting law is typically challenged as being ultra vires (beyond powers) the concerned legislature under Article 246.6 Repugnancy under Article 254, conversely, arises when both Parliament and the State Legislature are constitutionally competent to enact laws on the subject (i.e., a matter in the Concurrent List), but the provisions of their respective laws are inconsistent.6
3/3 Report Scope and Structure
This report provides an expert-level analysis of Article 254 of the Constitution of India. It commences with the full text of the Article, followed by a detailed examination of the doctrine of repugnancy, including its definition and the conditions under which it arises. The report then delves into the mechanism of Presidential assent provided under Article 254(2) and the overriding power retained by Parliament under the proviso. A significant portion is dedicated to analyzing the interpretation of Article 254 by the Supreme Court of India through landmark judgments. Furthermore, the report explores the crucial interlinkages between Article 254, Article 246, and the Seventh Schedule, assessing the impact of Article 254 on the federal balance of legislative power. Finally, it evaluates the role and significance of Article 254 within the broader context of Indian federalism and the principle of Parliamentary supremacy.
II. The Constitutional Provision: Text of Article 254
A. Presentation of Full Text
Article 254 of the Constitution of India reads as follows 15:
254. Inconsistency between laws made by Parliament and laws made by the Legislatures of States
(1) If any provision of a law made by the Legislature of a State is repugnant to any provision of a law made by Parliament which Parliament is competent to enact, or to any provision of an existing law with respect to one of the matters enumerated in the Concurrent List, then, subject to the provisions of clause…source any provision repugnant to the provisions of an earlier law made by Parliament or an existing law with respect to that matter, then, the law so made by the Legislature of such State shall, if it…source
B. Structural Breakdown
The structure of Article 254 is logical and hierarchical:
Clause (1): Establishes the general principle of Union supremacy in the event of a conflict between a State law and a competent Parliamentary law (or an existing law) concerning a matter in the Concurrent List. It declares the State law void to the extent of the repugnancy.
Clause (2): Carves out a specific exception to the general rule laid down in Clause (1). It allows a State law, despite being repugnant to an earlier Parliamentary law or existing law on a Concurrent List matter, to prevail within that State, contingent upon receiving Presidential assent after being reserved for consideration.
Proviso to Clause (2): Qualifies the exception in Clause (2). It reaffirms Parliament’s plenary power to legislate on the same Concurrent List matter subsequently, even to the extent of amending or repealing the State law that had received Presidential assent.
III. The Doctrine of Repugnancy: Defining Legislative Conflict
A. Meaning and Definition
The core concept underpinning Article 254 is ‘repugnancy’. In constitutional law, repugnancy signifies an inconsistency, incompatibility, contradiction, or direct opposition between the provisions of two different laws.6 It arises when laws enacted by two different legislative bodies, operating within a sphere of concurrent jurisdiction, cannot stand together.2 Black’s Law Dictionary defines “repugnant” as “inconsistent or irreconcilable with,” while Wharton’s Law Lexicon describes it as occurring when provisions in different laws conflict directly.6
Essentially, a situation of repugnancy emerges when applying two laws to the same set of facts yields contradictory outcomes, or when compliance with one law necessitates the violation of the other.2 It is this irreconcilable conflict in the concurrent field that Article 254 seeks to resolve.2
B. Conditions for Repugnancy
The Supreme Court of India, through numerous judgments, has delineated the conditions under which repugnancy can be said to exist between a Union law and a State law, primarily in the context of the Concurrent List.6 The mere possibility of conflict is insufficient; a demonstrable inconsistency is required. The key tests are:
Direct Conflict/Collision: There must be a clear and direct contradiction between the provisions of the Central Act and the State Act.2 The inconsistency must be “irreconcilable,” meaning the two laws are mutually exclusive and cannot be obeyed simultaneously.6 If it is possible to obey both laws without transgressing either, repugnancy generally does not arise.2
Occupying the Same Field: Both the Parliamentary law and the State law must operate in the same legislative field or pertain to the same subject matter.6 If the two laws deal with distinct aspects or operate in different domains, even if related, there might be no repugnancy. However, the laws need not fall under the identical entry in the Concurrent List if their substance covers the same ground.6
Intention to Cover the Field (Exhaustive Code): Repugnancy may also arise if Parliament, in enacting its law, intended to cover the entire subject matter comprehensively, leaving no room for State legislation in that field.6 If a Central law is deemed to be an exhaustive code on a particular subject in the Concurrent List, any State law on that subject, even if not directly contradictory in every detail, may be considered repugnant and thus void.2 This test focuses on the legislative intent behind the Parliamentary enactment.
These conditions were notably summarized by the Supreme Court in cases like M. Karunanidhi v. Union of India (1979) and derived from earlier pronouncements like Deep Chand v. State of U.P. (1959), which adapted principles from comparative constitutional law.2
The relatively high threshold established by the courts for finding repugnancy—requiring an “irreconcilable” conflict or “direct collision”—suggests a judicial preference for harmonious construction. Courts often endeavor to interpret Central and State laws in a manner that allows both to operate concurrently, thereby avoiding the invalidation of State legislation where possible.1 This interpretive approach can be seen as bolstering the federal principle by preserving State legislative space unless a conflict is unavoidable and absolute. The judgment in M. Karunanidhi, for instance, found that the State Act under challenge supplemented rather than contradicted the Central Acts, allowing both to stand.5
However, the principle that Parliament can ‘occupy the field’ introduces a significant dimension based on legislative intent.2 This allows Parliament to assert dominance over a Concurrent List subject by enacting legislation that is so comprehensive in scope that it implicitly signals an intention to exclude any State law in that area, even without direct contradiction in every clause.6 This serves as a potent tool for ensuring national uniformity when deemed necessary by Parliament. Landmark cases like Zaverbhai Amaidas v. State of Bombay (1954) and Forum for People’s Collective Efforts v. State of W.B. (2021) exemplify this, where State laws were invalidated because Parliament was deemed to have intended its legislation to be exhaustive in the respective fields.2
C. Scope of Invalidity
An important aspect of Article 254(1) is that it renders the State law void only “to the extent of the repugnancy”.1 This means that if only certain provisions of a State Act conflict with a Central Act, only those provisions become void, and the rest of the State Act may remain valid and enforceable, provided it can stand independently.2 The entire State statute is not automatically invalidated unless the repugnant provisions are inextricably linked to the rest of the Act.1
IV. The Presidential Assent Mechanism: Article 254(2)
A. The Exception to Parliamentary Supremacy
Article 254(2) provides a crucial, albeit conditional, exception to the general rule of Parliamentary supremacy established in Article 254(1).1 It allows a law made by a State Legislature concerning a matter in the Concurrent List to prevail within that specific State, even if its provisions are repugnant to those of an earlier law made by Parliament or an existing law (laws in force before the Constitution’s commencement) on the same matter.5 This mechanism acknowledges the possibility that a State may have legitimate reasons to enact legislation differing from pre-existing national norms on concurrent subjects.2
B. Conditions for Application
For a State law to benefit from the protection offered by Article 254(2), several conditions must be met cumulatively:
Concurrent List Matter: The State law must pertain to one of the matters enumerated in List III (Concurrent List) of the Seventh Schedule.1
Repugnancy with Earlier Central/Existing Law: The State law must contain provisions that are repugnant to the provisions of an earlier law made by Parliament or an existing law concerning that matter.1
Reservation for President’s Consideration: The Bill, after being passed by the State Legislature, must have been reserved by the Governor of the State for the consideration of the President of India.1
Receipt of President’s Assent: The President must have given his assent to the reserved Bill.6
If all these conditions are satisfied, the State law, despite its repugnancy to the earlier Central or existing law, will prevail and be operative within the boundaries of that particular State.1
C. The Role and Scope of Presidential Assent
The requirement of Presidential assent under Article 254(2) is not merely procedural; it involves substantive consideration. The President grants assent based on the aid and advice tendered by the Union Council of Ministers, as mandated by Article 74 of the Constitution.3 This effectively means that the Union executive plays a decisive role in determining whether a State should be permitted to deviate from an existing national legislative framework on a concurrent subject.
The Supreme Court, in the landmark case of Kaiser-I-Hind Pvt. Ltd. v. NTCL (2002), significantly clarified the scope of this assent. The Court ruled that the President’s assent under Article 254(2) is not a general validation of the State Act against all possible Central laws. Instead, the assent’s protective ambit is limited only to the specific repugnancy between the State law and the particular earlier Central law(s) or existing law(s) that were explicitly brought to the President’s notice and considered during the process of granting assent.22 If a State seeks assent by highlighting repugnancy with Central Act ‘A’, the assent received will not protect the State law from being repugnant to another Central Act ‘B’ if Act ‘B’ was not part of the consideration for assent.23 This necessitates legislative precision on the part of State governments when preparing their proposals for Presidential assent, clearly identifying the Central enactments with which conflict exists.23
While the act of giving or withholding assent by the President is generally considered non-justiciable (meaning courts cannot inquire into the adequacy of the reasons for the decision) 23, the process leading to it might be subject to limited judicial review, for instance, concerning procedural requirements or the proper application of constitutional provisions.24
This mechanism involving Presidential assent functions less as a purely legal adjudication and more as a politically mediated process for managing federal legislative tensions. The involvement of the Union executive allows for a consideration of the specific circumstances and justifications presented by the State, weighed against broader national policy objectives. It provides a structured channel for negotiation and accommodation within the federal system. However, the ultimate power retained by Parliament, as discussed below, ensures this accommodation remains conditional. The process can also be influenced by the prevailing political dynamics between the Centre and the State.25
D. The Proviso: Parliament’s Enduring Supremacy
Crucially, Article 254(2) is subject to a proviso. This proviso explicitly preserves the overriding legislative authority of Parliament.1 It states that even after a State law has received Presidential assent under Article 254(2) and prevails in that State, Parliament is not precluded from enacting any law with respect to the same matter at any time.4 Such subsequent Parliamentary legislation can add to, amend, vary, or even completely repeal the State law that had been assented to by the President.5
This proviso ensures that the exception carved out by Article 254(2) does not permanently dilute Parliament’s power in the Concurrent List. It underscores the principle that while states may be allowed temporary or specific deviations with Presidential approval, the ultimate legislative control over concurrent subjects rests with the Union Parliament. If Parliament deems it necessary, it can reassert uniformity or impose a different national standard by enacting a subsequent law that overrides the assented State law.4
Furthermore, the specific wording of Article 254(2), referring to repugnancy with “earlier law made by Parliament or an existing law,” is significant.1 This implies that the protection offered by Presidential assent primarily shields a State law from pre-existing Central legislation. If Parliament enacts a new law on the same Concurrent List subject after the State law has been enacted (and possibly even after it has received assent), the general rule of Parliamentary supremacy under Article 254(1), which applies irrespective of whether the Parliamentary law is passed “before or after” the State law, might come into play, potentially overriding the State law without needing to invoke the proviso specifically. The proviso reinforces this by explicitly allowing Parliament to legislate after the assent. This structure consistently upholds the legislative paramountcy of Parliament over time in the concurrent field.
V. Judicial Contours: Supreme Court‘s Interpretation of Article 254
A. The Judiciary’s Role
The judiciary, particularly the Supreme Court of India, plays a pivotal role in interpreting and applying Article 254.1 Through its judgments, the Court has clarified the meaning of repugnancy, established the tests for determining its existence, defined the scope of Presidential assent, and adjudicated numerous disputes involving conflicting Union and State laws.2 Judicial interpretation gives practical shape to the constitutional provisions governing legislative relations in the concurrent field.
B. Landmark Case Analyses
Several landmark judgments have shaped the understanding and application of Article 254:
Deep Chand v. State of U.P. (1959): This case involved a conflict between the Uttar Pradesh Transport Service (Development) Act and the Central Motor Vehicles Act. The Supreme Court held that since both laws occupied the same field (motor transport services), the State law was void to the extent of its repugnancy with the Central Act under Article 254(1).5 This case reinforced the ‘occupied field’ test and the principle of Central law prevailing in case of direct conflict.5
Zaverbhai Amaidas v. State of Bombay (1954): Here, the conflict arose from differing punishments prescribed by a Bombay Act and the Central Essential Supplies (Temporary Powers) Act for the same offence. The Supreme Court found repugnancy. Significantly, it also held that when Parliament subsequently amended the Central Act, it effectively ‘occupied the field’, implicitly repealing the repugnant State provision (which had received assent under the Government of India Act, 1935 framework). This highlighted that subsequent Parliamentary action could override even previously validated State laws.2
M. Karunanidhi v. Union of India (1979): This case involved the Tamil Nadu Public Men (Criminal Misconduct) Act and Central laws like the Indian Penal Code and the Prevention of Corruption Act. The Court provided a comprehensive summary of the tests for repugnancy, emphasizing that repugnancy arises only if the conflict is direct and irreconcilable.5 It held that if the State law is merely supplemental to the Central law and does not contradict it, there is no repugnancy.20 The Court found no repugnancy in this instance, holding that the State Act could coexist with the Central Acts.2 The Court also touched upon the application of the ‘pith and substance’ doctrine to ascertain the true nature of the legislation before considering repugnancy.5
Hoechst Pharmaceuticals Ltd. v. State of Bihar (1983): The Court clarified that Article 254 is primarily concerned with conflicts arising within the Concurrent List (List III).2 Conflicts between laws made under the State List (List II) and the Union List (List I) or Concurrent List (List III) should first be examined under Article 246 using the doctrine of ‘pith and substance’ to determine legislative competence.21 Only if both legislatures are found competent under the Concurrent List does the question of repugnancy under Article 254 arise. The Court reiterated that repugnancy implies that obedience to one law entails disobedience to the other.21
Kaiser-I-Hind Pvt. Ltd. v. NTCL (2002): This judgment provided a crucial interpretation of Article 254(2). The Supreme Court held that Presidential assent granted to a State law is limited in scope. It protects the State law only against repugnancy with those specific earlier Central laws or existing laws that were mentioned in the State’s proposal and considered by the President while granting assent. It does not provide blanket immunity against other Central laws.22
Forum for People’s Collective Efforts v. State of W.B. (2021): The Court struck down the West Bengal Housing Industry Regulation Act, 2017 (WB-HIRA) as unconstitutional. It found that WB-HIRA was “virtually identical” to the Central Real Estate (Regulation and Development) Act, 2016 (RERA) and thus occupied the same field in the Concurrent List.6 In the absence of Presidential assent under Article 254(2), the State Act was held to be repugnant to the Central Act and therefore void. This case strongly reaffirmed the ‘occupied field’ test as a ground for repugnancy, even where provisions are largely similar rather than directly contradictory.19
The judicial approach, while consistently upholding the principle of Parliamentary supremacy enshrined in Article 254(1) and the proviso to 254(2), often involves a meticulous examination of the specific facts and legislative provisions in each case. Courts scrutinize whether the laws genuinely conflict or if they can be interpreted harmoniously, and whether they truly operate within the same legislative domain.20 This case-by-case determination allows for nuanced application of the constitutional principles but can also lead to a degree of uncertainty regarding the validity of State legislation until it withstands judicial scrutiny, potentially leading to litigation.17
Furthermore, a contemporary issue gaining judicial attention is whether the doctrine of repugnancy under Article 254 extends to conflicts between a State law and delegated legislation (such as rules or regulations) framed under a Central Act.25 Article 254 explicitly refers to “law made by Parliament” and “law made by the Legislature of a State”. Extending its scope to include delegated legislation, which is typically made by the executive branch under authority granted by the legislature, could significantly broaden the scope of Central power and potentially subject State statutes to rules framed by the Union executive, raising complex questions about federal balance and the separation of powers.25
C. Table: Summary of Key Supreme Court Cases on Article 254
Repugnancy due to conflicting penalties; effect of subsequent Parliamentary amendment.
Subsequent Parliamentary law occupying the same field impliedly repeals repugnant State law provision, even if previously assented under prior regime. Central law prevails.
Established ‘occupied field’ by subsequent legislation as a form of repugnancy leading to implied repeal.
Deep Chand v. State of U.P.
1959
Motor Vehicles Act, 1939
U.P. Transport Service (Development) Act, 1955
Motor Vehicles / Transport Services
Repugnancy where both laws occupy the same field.
State law void under Art 254(1) to the extent of repugnancy when both laws operate in the same field and conflict.
Reinforced the ‘occupied field’ test and the general rule of Parliamentary supremacy under Art 254(1).
M. Karunanidhi v. Union of India
1979
Indian Penal Code, 1860; Prevention of Corruption Act, 1947
Tamil Nadu Public Men (Criminal Misconduct) Act, 1973
Criminal Law / Prevention of Corruption
Tests for determining repugnancy; coexistence of laws.
No repugnancy if laws are supplemental and not directly contradictory. Repugnancy requires irreconcilable conflict. State Act upheld as complementary.
Provided comprehensive tests for repugnancy, emphasizing need for direct, irreconcilable conflict and allowing for supplementary State legislation.
Hoechst Pharmaceuticals Ltd. v. State of Bihar
1983
Essential Commodities Act, 1955 (Drugs Price Control Order)
Bihar Finance Act (Surcharge on Sales Tax)
Price Control (List III) vs. State Taxation (List II)
Applicability of Art 254 to conflict between List II and List III laws. Test for repugnancy.
Art 254 primarily applies to List III conflicts. Conflicts between Lists resolved by Art 246 & pith and substance. Repugnancy arises if simultaneous obedience is impossible.
Clarified that Art 254 applies mainly to Concurrent List conflicts; emphasized impossibility of obedience test.
Kaiser-I-Hind Pvt. Ltd. v. NTCL
2002
Public Premises (Eviction) Act, 1971; other Central Acts
Bombay Rents, Hotel and Lodging House Rates Control Act, 1947
Rent Control / Eviction
Scope of Presidential assent under Art 254(2).
Presidential assent under Art 254(2) is limited to the specific repugnancy with earlier Central/existing laws mentioned in the State’s proposal for assent.
Crucially limited the protective scope of Presidential assent, requiring specificity in proposals.
Forum for People’s Collective Efforts v. State of W.B.
2021
Real Estate (Regulation and Development) Act, 2016 (RERA)
West Bengal Housing Industry Regulation Act, 2017 (WB-HIRA)
Contracts / Transfer of Property (Real Estate Regulation)
Repugnancy due to State law being ‘virtually identical’ to Central law occupying the field.
State law occupying the same field as an exhaustive Central law is repugnant under Art 254(1) and void without Presidential assent under Art 254(2).
Reaffirmed ‘occupied field’ as a strong ground for repugnancy, even without direct contradiction, striking down a parallel State regulatory regime lacking Presidential assent.
VI. Constitutional Interlinkages: Article 254, Article 246, and the Seventh Schedule
A. The Foundation: Article 246 and the Seventh Schedule
The distribution of legislative powers between the Union and the States forms the bedrock of India’s federal structure, primarily articulated through Article 246 of the Constitution.8 This Article operationalizes the division of subjects enumerated in the Seventh Schedule into three distinct lists 10:
List I (Union List): This list contains subjects of national importance, such as defence, foreign affairs, currency, banking, railways, and atomic energy.9 Parliament has exclusive power to make laws with respect to any matter enumerated in this list.8
List II (State List): This list includes matters of regional or local importance, such as public order, police, public health, agriculture, land, and local government.10 Subject to certain exceptions outlined elsewhere in the Constitution (e.g., Articles 249, 250, 252), the Legislature of a State has exclusive power to make laws for that State with respect to matters in this list.8
List III (Concurrent List): This list comprises subjects where uniformity of law across the country is desirable but not essential, allowing for both national standards and state-specific adaptations. Examples include criminal law and procedure, civil procedure, marriage and divorce, contracts, bankruptcy, trade unions, education, forests, and electricity.10 Both Parliament and the State Legislatures have the power to make laws on matters enumerated in this list.8
Article 246 thus lays down the fundamental framework defining who can legislate on what subjects.12
B. Article 254’s Operational Sphere
Article 254 operates specifically within the legislative domain carved out by Article 246, but its direct application is confined primarily to situations involving the Concurrent List (List III).1 When both Parliament and a State Legislature enact laws on a subject found in the Concurrent List, and their provisions conflict, Article 254 provides the rule to determine which law will prevail.5
It is generally established, as affirmed in Hoechst Pharmaceuticals21, that Article 254 does not directly resolve conflicts arising from an encroachment by one legislature upon the exclusive list of another (e.g., a State law encroaching on the Union List, or vice versa). Such situations are typically analyzed under Article 246 through the doctrine of ‘pith and substance’.6 This doctrine seeks to determine the true nature and character of the legislation. If a law substantially falls within the legislative competence of the enacting legislature, it is not deemed invalid merely because it incidentally touches upon a matter assigned to the other legislature.6 If, however, the encroachment is substantial and not merely incidental, the law may be declared ultra vires for lack of legislative competence, rendering the question of repugnancy under Article 254 irrelevant.7
C. Interplay and Hierarchy
The interplay between Article 246 and Article 254 reveals a clear constitutional hierarchy. Article 246 first defines the respective legislative fields.10 Article 254 then steps in to manage conflicts specifically within the shared legislative space—the Concurrent List—where both Parliament and State Legislatures are competent to act.1 Therefore, the question of repugnancy under Article 254 arises only after it is determined that both the Union and the State legislatures possess the legislative competence under Article 246 (read with the Concurrent List) to enact their respective laws.6 Once competence is established for both, Article 254 dictates the outcome in case of inconsistency.
This structured approach—first defining legislative domains and then providing a specific conflict-resolution rule for the shared domain—reflects a deliberate constitutional design. It prioritizes clear allocation of exclusive powers where feasible (Lists I and II) but acknowledges the need for concurrent powers (List III). Within this concurrent sphere, the Constitution establishes a default rule favouring the Centre (Article 254(1)), consistent with the principle of federal supremacy embedded in the non-obstante clauses of Article 246 itself (“Notwithstanding anything in clauses (2) and (3)…” in 246(1), and “Notwithstanding anything in clause (3)…” in 246(2)).8 This systematic structure points towards a preference for central authority when legislative powers overlap and conflict.
VII. Federal Implications: Article 254 and the Balance of Legislative Power
Article 254 significantly shapes the legislative relationship between the Union and the States, particularly concerning the Concurrent List, which covers many vital areas of governance.1 Clause (1) clearly establishes the legislative supremacy of Parliament in this shared domain.6 If a State law conflicts with a Parliamentary law on a concurrent subject, the State law must yield, ensuring that national legislation prevails.6 This provision acts as a strong centralizing force, enabling the Union Parliament to set national standards and override divergent state laws when it deems necessary.10
However, Article 254(2) introduces a crucial counter-balance, providing States with a mechanism to assert a degree of legislative autonomy.1 By obtaining Presidential assent for a State law that is repugnant to an earlier Central law on a concurrent subject, a State can carve out an exception for itself, allowing its law to prevail within its territory.2 This enables States to legislate according to their specific regional needs, socio-economic conditions, or policy preferences, even if they differ from existing national legislation.3
The interplay between these two clauses creates a dynamic tension. While the default position favours the Union, the exception provides a pathway for States to legislate differently, subject to approval mediated by the Union executive (via Presidential assent).4 The proviso to Clause (2), however, ensures that this state autonomy is not absolute and can be subsequently overridden by Parliament, reaffirming the ultimate legislative paramountcy of the Union.1
B. Balancing Uniformity and Diversity
Article 254 embodies the inherent tension in a large and diverse federal country like India: the need for national uniformity versus the accommodation of regional diversity.1 Parliamentary supremacy under Article 254(1) facilitates uniformity, ensuring that certain basic laws or national policies apply consistently across the country. This is particularly important for subjects in the Concurrent List that have significant inter-state implications or require a unified national approach.
Conversely, Article 254(2) allows for diversity.17 It permits States, with the Centre’s concurrence (via Presidential assent), to enact laws tailored to their unique circumstances.19 For example, States might seek assent for amendments to central laws like the Code of Criminal Procedure or the Code of Civil Procedure to address specific local issues, or they might enact laws on subjects like education or labour welfare that differ from earlier Central enactments based on regional requirements. The recent controversies surrounding state amendments to central land acquisition laws illustrate this dynamic vividly, where states have sought to modify the national framework to suit their development priorities.17
However, the practical application of Article 254(2) can lead to a complex legal landscape. While allowing flexibility, the successful use of the Presidential assent mechanism by multiple states for varying laws on the same concurrent subject can result in a ‘patchwork’ of legislation across India.17 This can undermine the very purpose of having a Concurrent List for matters requiring some degree of national consistency and can create challenges in legal interpretation, compliance, and inter-state coordination. The example of Tamil Nadu reportedly exempting a large percentage of land acquisitions from the central LARR Act highlights how state autonomy exercised under this framework can lead to significant divergence from national norms.17
C. The ‘Quasi-Federal’ Nature
The functioning of Article 254 is a clear manifestation of India’s ‘quasi-federal’ constitutional character, which blends federal features with strong unitary or centralizing elements.3 The division of powers in the Seventh Schedule is a federal feature, but the Concurrent List itself, coupled with the mechanism in Article 254 that ultimately favours Parliamentary law, demonstrates the Constitution’s centralizing tilt. Article 254(1) and the proviso to Article 254(2) ensure that in the crucial sphere of concurrent legislation, the Union Parliament holds the dominant position.
The mechanism of Article 254, particularly the dynamic interplay between clauses (1) and (2), institutionalizes a continuous process of negotiation, potential conflict, and resolution regarding legislative space in the Concurrent List. It is not merely a static rule but an active arena where the practical balance of power between the Centre and the States is constantly tested and redefined.17 The frequency and manner in which States seek Presidential assent, the Union executive’s response, and Parliament’s potential use of its overriding power under the proviso all reflect the prevailing political realities and the state of Centre-State relations at any given time.25 This makes Article 254 a key site where the operational dynamics of Indian federalism unfold.
VIII. Evaluating Article 254: Role in Indian Federalism and Parliamentary Supremacy
A. Upholding Parliamentary Supremacy
Article 254 undeniably plays a critical role in upholding the principle of Parliamentary supremacy within India’s constitutional framework, particularly concerning the Concurrent List.1 The default rule established in Article 254(1) ensures that in case of any irreconcilable conflict between a State law and a Parliamentary law on a concurrent subject, the Parliamentary law prevails.6 Furthermore, the proviso to Article 254(2) acts as a powerful reinforcement of this supremacy, explicitly preserving Parliament’s authority to legislate on a concurrent matter at any time, even if it means overriding a State law that had previously secured Presidential assent.10 This ensures that the Union legislature retains the final say in shaping laws on subjects deemed important enough to be placed in the Concurrent List.
B. Facilitating Cooperative Federalism?
The role of Article 254 in fostering cooperative federalism is debatable. On one hand, the mechanism under Article 254(2), requiring a State to reserve a repugnant Bill for Presidential assent, necessitates interaction between the State government and the Union executive (which advises the President).3 This process could potentially foster dialogue and negotiation, allowing the Centre to understand the State’s specific needs and rationale for deviating from a Central law, leading to an agreed-upon outcome.
However, the process can also be a source of friction.33 The decision on assent rests with the President acting on the advice of the Union government, which can lead to perceptions of political bias, particularly if the State and Centre are ruled by different political parties.25 Moreover, the ever-present possibility of Parliament overriding an assented State law using the proviso can undermine the spirit of cooperation and create uncertainty for the States.1 The power dynamics inherent in the process, weighted heavily in favour of the Centre, may hinder rather than promote genuine cooperation on equal terms.
C. Effectiveness as a Conflict Resolution Mechanism
As a mechanism for resolving Centre-State legislative conflicts in the concurrent field, Article 254 provides a clear legal framework and hierarchy.1 It establishes a default rule (Union supremacy) and a specific exception (State law prevailing with Presidential assent), along with an ultimate override power for Parliament. In this sense, it offers a definitive pathway for resolving inconsistencies.
However, its effectiveness can be questioned due to the complexities and potential for litigation arising from its interpretation.28 Determining whether repugnancy actually exists, whether laws occupy the same field, or whether Parliament intended an exhaustive code often requires judicial interpretation, leading to delays and uncertainty.17 The high threshold for proving “irreconcilable conflict” can sometimes allow overlapping laws to coexist uneasily. Furthermore, the political nature of the Presidential assent process can introduce elements beyond purely legal considerations.
D. Contemporary Relevance and Challenges
Article 254 remains highly relevant in contemporary India, as both Parliament and State Legislatures continue to actively legislate on Concurrent List subjects. Issues like environmental regulation, education policy, agricultural reforms, land acquisition, and amendments to criminal and civil procedure frequently involve potential applications of Article 254.10
A significant contemporary challenge revolves around the potential application of Article 254 to conflicts involving delegated legislation promulgated by the Union government under a Parliamentary Act.25 If Central rules or regulations are held capable of rendering a Statestatute repugnant under Article 254(1), it would represent a substantial expansion of Central power over State legislatures, bypassing the Parliamentary legislative process itself.25 Additionally, there are ongoing debates and demands from some States for a restructuring of Centre-State legislative relations, potentially involving revisiting the lists in the Seventh Schedule or the mechanisms for conflict resolution like Article 254, aiming for greater state autonomy.10
Ultimately, while Article 254 provides a necessary framework for managing legislative conflicts inherent in India’s concurrent legislative sphere, it simultaneously reflects and potentially perpetuates the underlying tensions between central authority and state autonomy. The manner in which Article 254 is invoked, interpreted by the courts, and operationalized through the Presidential assent process serves as a sensitive barometer of the prevailing federal climate in India.33 Periods of centralized political power might see a stronger assertion of Parliamentary supremacy, while periods marked by stronger regional forces might witness more frequent use or demands for the application of the exception under Article 254(2).33 The ongoing legal and political engagement with Article 254 underscores its enduring significance in shaping the contours of Indian federalism.
IX. Conclusion
A. Synthesis of Key Findings
Article 254 of the Constitution of India is a critical provision governing the complex legislative relationship between the Union and the States within India’s quasi-federal structure. Its core elements include:
The Doctrine of Repugnancy: It addresses inconsistencies between laws made by Parliament and State Legislatures on matters within the Concurrent List. Repugnancy arises when there is a direct, irreconcilable conflict, when both laws occupy the same field, or when Parliament intends its law to be an exhaustive code.
Parliamentary Supremacy (Article 254(1)): As a general rule, if a State law is repugnant to a Parliamentary law on a concurrent subject, the Parliamentary law prevails, and the State law is void to the extent of the repugnancy.
Presidential Assent Exception (Article 254(2)): An exception allows a State law, repugnant to an earlier Parliamentary law or existing law on a concurrent matter, to prevail within that State if it has been reserved for and received the President’s assent.
Parliament’s Overriding Power (Proviso to Article 254(2)): Parliament retains the ultimate authority to enact subsequent legislation on the same concurrent matter, which can amend, vary, or repeal the assented State law.
Judicial Interpretation: The Supreme Court has played a vital role in defining the tests for repugnancy (requiring direct and irreconcilable conflict, or occupation of the same field) and clarifying the scope of Presidential assent (limited to specifically considered repugnancies).
B. Final Assessment
Article 254 serves as an essential, albeit complex, mechanism for managing the inevitable legislative overlaps inherent in the Concurrent List. It provides a framework that fundamentally upholds Parliamentary supremacy, ensuring the Union’s ability to maintain national standards and legislative uniformity when necessary. This reflects the Constitution’s overall design, which, while federal in structure, contains significant centralizing features.
Simultaneously, Article 254(2) offers a crucial, though conditional, window for state legislative autonomy, allowing States to tailor laws to specific regional contexts, subject to the concurrence of the Union executive expressed through Presidential assent. This exception acknowledges the diversity of India and the need for flexibility in governance.
However, the operation of Article 254 is not without challenges. The determination of repugnancy often requires intricate judicial interpretation, leading to potential litigation and uncertainty. The Presidential assent mechanism, being politically mediated, can be a source of Centre-State friction. The ultimate overriding power of Parliament ensures central dominance but can limit the durability of state-level legislative innovations.
In conclusion, Article 254 is more than just a technical rule for resolving legislative conflicts. It is a dynamic provision that lies at the heart of India’s federal balance. Its application and interpretation reflect the ongoing negotiation between central authority and state autonomy, making it a critical indicator of the functional realities of Indian federalism. While providing a necessary framework for managing legislative concurrency, it embodies the tensions and complexities inherent in governing a large, diverse nation through a quasi-federal constitutional structure.